Property Investing Advice and Market Insights.

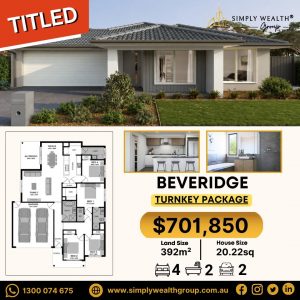
4 Bedroom House and Land Beveridge — Titled, $701,850

4 Bedroom House and Land Beveridge — Titled, Alfresco Living, Ready to Build Waiting on a title is one of the most frustrating parts of buying house and land. Not with this one. This 4 bedroom house and land Beveridge package comes with the title already secured, so the land is ready and construction can move forward without the usual paperwork delays. For families and investors who want certainty and a faster path to build, that head start matters. Set on a generous 392m² block with a 20.22sq home footprint, this design is built around the way families actually live. A large family and meals zone sits at the heart of the home, flowing out to an alfresco that extends your entertaining space outdoors. Four well-sized bedrooms give everyone room to spread out, whether that means kids with their own space, a dedicated home office, or a guest room for visiting family. What’s included: 4 bedrooms 2 bathrooms 2 car garage Alfresco entertaining area Large family and meals zone Land Size: 392m² House Size: 20.22sq Priced at $701,850, this 4 bedroom house and land Beveridge package is a genuine alternative to waiting on an off-the-plan release, where buyers can spend months or even years before a build begins. Why Titled Land Matters A titled block means the land has been registered, so there is no waiting on subdivision approvals or registration before construction can start. Every month spent waiting on a title is a month of holding costs and uncertainty, with nothing to show for it. Buying titled land removes that risk and gives you a clearer, more predictable timeline from signing to keys in hand. For investors, an earlier build start means an earlier completion and an earlier start to rental income. For families, it means a shorter wait before moving into a home with room to grow, and less time juggling rent and mortgage commitments at the same time. Alfresco Living and a Family-First Layout The alfresco is where this design earns its keep. Weekend barbecues, kids playing within sight of the kitchen, relaxed evenings outdoors: an alfresco connected to the family and meals zone turns the whole back of the home into one flexible entertaining space. It is one of the features buyers ask about most, and it adds real everyday value without the cost of a separate outdoor build later. With four bedrooms and two bathrooms, the layout also works for a range of households. Growing families get space to grow into, while investors get a floorplan that appeals to renters who want size, comfort, and a proper outdoor area. Why Beveridge? Beveridge continues to be one of Melbourne’s standout northern growth corridor suburbs, with ongoing investment in schools, transport, and retail supporting long-term demand. Buyers who secure land here now are positioned ahead of much of that rollout, which has historically been where the strongest land value growth occurs. A 4-bedroom, 2-bathroom, 2-car home in this configuration is consistently in demand across both the family and rental markets. Larger blocks like this 392m² allocation also give buyers more breathing room than the compact lots common in newer estates. Why Go Turnkey? A turnkey package bundles land, construction, driveway, fencing, and landscaping into one fixed price before you sign. That means no juggling separate contracts and no mid-build cost surprises. Combined with titled land, you get two layers of certainty: a locked-in price and a build that is ready to progress. In a market where construction costs and trade availability have made timelines unpredictable for buyers managing their own builds, that certainty is hard to overstate. Who This Package Suits Growing families needing four real bedrooms and a large living zone Investors wanting a titled, ready-to-build asset with strong rental appeal Upgraders moving from a smaller home into proper family-sized space Buyers who value certainty and want to avoid titling delays Move Forward Today With the title already in hand, this Beveridge turnkey package is ready to progress. Allocations are limited, and titled stock tends to move quickly. If you want a faster path to build, now is the time to act. 📲 WhatsApp us: Message us here 📞 Call: 1300 074 675 🌐 Visit: www.simplywealthgroup.com.au
Read More »

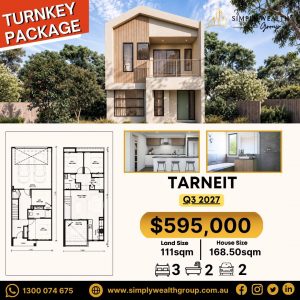
Tarneit House and Land Package — 3 Bed, $595,000

Tarneit House and Land Package — Double-Storey Turnkey Living, Ready Q3 2027 Looking for a modern, low-maintenance home in one of Melbourne’s busiest western growth suburbs? The Tarneit house and land package is Simply Wealth Group’s newest turnkey release: a double-storey, townhouse-style home with a striking timber-look facade, a private balcony, and a smart layout spread across two levels. It’s built for first home buyers and investors who want a fixed price, a fixed completion date, and a property that looks sharp from the day the keys are handed over. Set on a 111m² block with a 168.50m² home footprint, this design proves that a compact lot doesn’t have to mean a compromised home. By building up rather than out, the floorplan delivers generous internal space while keeping the land size, and the price, at a level that makes entry into the market far more achievable. The two-level layout separates living and sleeping zones naturally, giving the home a comfortable, well-organised feel that works for everyday routines, whether you’re hosting friends downstairs or winding down upstairs. What’s included: 3 bedrooms 2 bathrooms 2 car garage Double-storey townhouse-style design Timber-look facade with private balcony Sleek, modern kitchen and stylish bathroom Priced at $595,000, this Tarneit house and land package is locked in for Q3 2027 completion. The price you see today is the price you pay, with no surprise costs between contract and handover. That kind of certainty matters, especially for buyers working within a fixed budget and a finance approval that leaves little room for blowouts. Why a Double-Storey Townhouse-Style Home? Townhouse-style homes have become one of the most popular options for buyers who want a modern build without the cost and upkeep of a large block. A smaller lot means less garden to maintain, lower land costs, and a home that is easy to lock up and leave. The second storey adds genuine living space, and the balcony gives you an outdoor spot to unwind without needing a big backyard. For first home buyers, that combination often means a lower purchase price and a more manageable loan. For investors, a low-maintenance 3-bedroom, 2-bathroom home with a double garage appeals to a wide tenant pool, from young families to couples and professionals who want space without the upkeep. Homes that suit a broad range of renters also tend to be easier to lease, which helps keep vacancy periods short. Why Tarneit? Tarneit is one of Melbourne’s most established and in-demand western growth corridor suburbs. It offers a train station, schools, shopping precincts, and ongoing infrastructure investment, which keeps demand strong from both owner-occupiers and renters. Buyers who want convenience and connection to the city, without paying inner-suburb prices, consistently put Tarneit near the top of their list. That sustained demand makes a Tarneit house and land package attractive from an investment point of view as well. Well-located, low-maintenance homes in established growth suburbs tend to attract tenants quickly, which can help reduce vacancy and keep cash flow steady. Buying into a suburb that already has the amenities in place also means less reliance on future infrastructure promises, since much of what residents need is already on the doorstep. Why Go Turnkey? A turnkey package removes the biggest source of stress in building a home: coordination. Instead of managing separate contracts for land, construction, driveway, fencing, and landscaping, everything is bundled into one fixed price before you sign. That protects you from rising construction costs and shifting timelines, both real risks for buyers managing a build on their own. With a Q3 2027 completion locked in, you also get time to plan. First home buyers can finalise their finance and build up their savings, while investors can line up property management and a tenant well ahead of handover. Knowing the date and the price from day one makes it far easier to budget, plan your move, or forecast rental income with confidence. Low-Maintenance Living, Without the Compromise Lower maintenance doesn’t have to mean lower quality. With a sleek kitchen, a stylish bathroom, and a timber-look facade that gives the home real street appeal, this design delivers the finishes buyers actually notice. Without a large yard to manage, weekends are yours again: no mowing, no endless garden jobs, just more time for family, friends, and the things you’d rather be doing. For investors, the same easy-care footprint means fewer ongoing costs and fewer reasons for tenants to move on, which supports longer, steadier leases. Who This Home Suits This Tarneit house and land package is built for: First home buyers wanting an affordable, modern entry point with no maintenance headaches Investors after a low-maintenance asset in a high-demand growth suburb Young couples and small families who want space across two levels without a large block Downsizers looking for a stylish, easy-care home with a double garage Busy professionals who value a lock-and-leave lifestyle close to transport and shops Secure Your Spot Allocations for this Tarneit house and land package are limited, and Q3 2027 completion slots won’t stay open for long. If you’ve been looking for a modern, well-located entry point into Melbourne’s west, this is worth acting on before the next price adjustment closes the door on today’s pricing. Enquire today to lock it in. 📲 WhatsApp us: Message us here 📞 Call: 1300 074 675 🌐 Visit: www.simplywealthgroup.com.au

Read More »

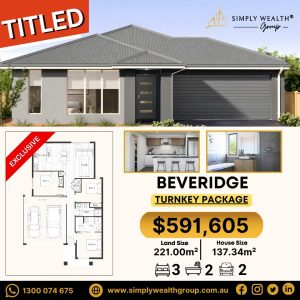
Titled Land Beveridge — 3 Bed Turnkey Package, $591,605

Titled Land Beveridge — Ready to Build Now, No Waiting Most buyers lose months waiting on a title before construction can even start. Not here. This titled land Beveridge package comes with the title already secured — land ready, paperwork done, nothing standing between you and a start date. For buyers who’ve been burned by titling delays before, or investors who simply don’t want to gamble on when construction might actually begin, that certainty alone sets this release apart from the majority of packages currently on the market. The home itself is a compact, well-designed 3-bedroom turnkey package built for exactly the kind of buyer who wants quality without excess — first home buyers taking their first step into ownership, and investors after a low-maintenance asset with broad rental appeal. The floor plan has been kept smart and efficient, giving every room a clear purpose without wasted space driving up the price. It’s a layout designed to feel open and functional rather than tight, even at a modest footprint. What’s included: 3 bedrooms 2 bathrooms 2 car garage Land Size: 221.00m² House Size: 137.34m² Priced at $591,605, this titled land Beveridge package is ready to move forward immediately — a genuine point of difference from off-the-plan packages where buyers wait years before construction can even start, often with no clear end date in sight. Why Titled Land Changes Everything Titling delays are one of the most frustrating — and costly — parts of buying house and land. Every month spent waiting on paperwork is a month of holding costs accruing on a block that isn’t producing anything. This Beveridge release skips that entirely. With the title already in hand, construction can begin immediately, meaning buyers reach completion, and start living in or renting out the property, considerably faster than a comparable untitled release still working through subdivision and registration. For investors, that timing advantage is direct and measurable: less time paying interest on land with no return, and an earlier start to rental income once the build is complete. Every month saved on a titling delay is effectively a month of extra cash flow over the life of the investment. For first home buyers, it means a shorter, more predictable path from signing to moving in — without the open-ended uncertainty that often comes with titling timelines entirely outside anyone’s control, including the builder’s. Why Beveridge? Beveridge continues to be one of Melbourne’s strongest-performing northern growth corridor suburbs, with ongoing investment in schools, transport, and retail infrastructure supporting sustained demand. As the suburb matures, buyers securing titled land now — rather than waiting on a future release — are positioning themselves ahead of much of that infrastructure rollout, which has historically been where the strongest land value growth occurs. A 3-bedroom, 2-bathroom, 2-car home in this configuration appeals to a wide range of buyers, from first home buyers wanting a manageable entry point to investors targeting tenants who want an affordable, well-located rental in a growing suburb. That broad appeal also tends to mean lower vacancy risk down the track, since the home suits a wide cross-section of the rental market rather than a narrow buyer profile. Why Go Turnkey, With Title Already Secured A turnkey package already removes the hassle of coordinating separate contracts for land, construction, driveway, fencing, and landscaping — everything bundled into one fixed price before you sign. Pairing that with titled land removes the other major source of delay and uncertainty in the process. Together, that means a faster, more predictable path from decision to keys in hand, with far less exposure to rising construction costs or shifting timelines along the way. In a building market where material costs and trade availability have made timelines genuinely unpredictable for buyers managing a build independently, having both the title and the price locked in before you sign is about as much certainty as you can realistically secure. Who This Package Suits This titled land Beveridge package is built for: First home buyers wanting a genuinely manageable entry point with no titling wait Investors after a faster path to rental income thanks to titled land Buyers who’ve been frustrated by titling delays on other packages elsewhere Anyone wanting certainty — a fixed price, titled land, and a clear path to construction starting now, not at some undefined point in the future Move Forward Today With the title already secured, this Beveridge turnkey package is ready to progress immediately — a genuine advantage over buyers still waiting on paperwork elsewhere. Allocations are limited, and titled stock like this tends to move faster than standard releases once buyers realise what the time savings are actually worth. 📲 WhatsApp us: Message us here 📞 Call: 1300 074 675 🌐 Visit: www.simplywealthgroup.com.au #Melbourne #FirstHomeBuyer #Investors #Australia #Titled #Beveridge #PropertyInvestment

Read More »

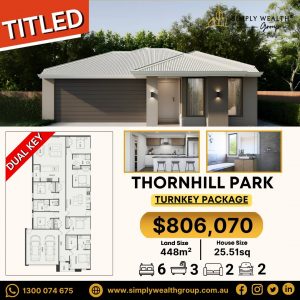
Dual Occupancy Thornhill Park — Titled Dual Key Package, $806,070

add 100 more words Dual Occupancy Thornhill Park — Two Incomes, One Title, Zero Wait Most dual key buyers spend months waiting on a title before they can even break ground. Not here. This dual occupancy Thornhill Park package comes with the title already secured — land ready, paperwork done, nothing standing between you and construction starting now. In a market where titling delays routinely blow out project timelines by six months or more, that alone puts this release ahead of almost every comparable dual key package currently on offer. The design itself is built for one purpose: maximum return from a single block. Two fully self-contained living spaces sit under one roof, each with its own entry, living area, and amenities — completely independent of each other. Whether you’re chasing two separate rental incomes, housing parents or adult children while keeping everyone’s privacy intact, or living in one side while the other pays down your mortgage, this layout does the heavy lifting. What you’re getting: 6 bedrooms, split across two dwellings 3 bathrooms 2 separate living areas 2 car garage Land Size: 448m² House Size: 25.51sq At $806,070, with title already in hand, this is one of the few dual occupancy Thornhill Park releases where you’re not gambling on a titling timeline before construction can start. The Real Value of Dual Occupancy Buy one block, get two income streams — that’s the entire appeal in one sentence. No subdividing, no managing two separate titles, no doubling your loan or your holding costs. Just one purchase, one mortgage, and two independently leasable dwellings working for you from day one. Run the numbers and the difference is obvious: a single-dwelling package gives you one rent cheque. This gives you two, from the same land cost. For investors focused on yield rather than just capital growth, that’s a materially different return profile — and one that becomes even more compelling as interest rates and holding costs keep affordability front of mind for buyers across Melbourne. Titled Means Moving Now, Not Later Titling delays are one of the biggest hidden costs in property investment — every month spent waiting is a month of interest accruing on land that isn’t producing a cent. This package removes that risk entirely. Construction can begin immediately, which means both dwellings reach completion, and start earning rent, faster than almost any comparable off-the-plan dual key release on the market right now. For investors comparing packages side by side, that timing advantage alone can be worth thousands in avoided holding costs before the first tenant even moves in. Why Thornhill Park Thornhill Park sits in one of Melbourne’s western growth corridors currently seeing genuine infrastructure investment — new transport links, schools, and retail precincts progressively coming online. That kind of growth trajectory is exactly where dual key properties perform best, with strong, steady rental demand from singles, couples, and smaller households priced out of larger homes elsewhere. As the suburb continues to build out, buyers securing a titled block now are positioning themselves ahead of the infrastructure curve rather than behind it. Who This Is For Investors wanting two rental incomes from one purchase Multi-generational families needing separate, private living spaces without splitting the household across two properties Owner-occupiers looking to live in one dwelling and let the second offset their repayments Buyers who don’t want to wait on titling before construction can start Ready Now — Not Someday Title in hand, construction ready to go, allocations limited. If you’ve been waiting for a dual key opportunity without the usual delays baked in, this is it — and with titled dual key stock this scarce, packages like this one tend to move quickly once word gets out. 📲 WhatsApp us: Message us here 📞 Call: 1300 074 675 🌐 Visit: www.simplywealthgroup.com.au #Melbourne #DualKey #Investors #Australia #Titled #ThornhillPark #PropertyInvestment

Read More »

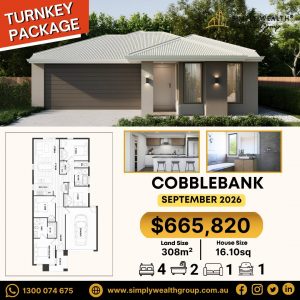
Cobblebank House and Land Package — 4 Bed, $665,820

Cobblebank House and Land Package — Space, Quality, and a Fast Track to Moving In Some homes make you wait years to move in. This one doesn’t. The Cobblebank house and land package from Simply Wealth Group is a turnkey release built for families and investors who don’t want to gamble on shifting construction timelines — with completion locked in for September 2026, one of the earliest handover dates across our current releases. On a 308m² block with a 16.10sq home footprint, this design was clearly built with real family life in mind rather than a bare-minimum checklist. Four bedrooms give everyone their own corner, the living area has genuine room to breathe, and the finishes throughout carry a level of quality that punches above the price point. It’s the kind of home that looks and feels considered, not cookie-cutter. What you’re getting: 4 bedrooms 2 bathrooms 1 car garage Sleek, modern kitchen Stylish bathroom Spacious living area with quality finishes throughout At $665,820, this Cobblebank house and land package is fixed — what’s quoted today is what you pay at settlement. No creeping costs, no renegotiating halfway through a build, no surprises. The Cobblebank Advantage Cobblebank has quietly become one of the standout suburbs in Melbourne’s western growth corridor — not because it’s the newest release area, but because the groundwork is already being laid: schools, transport, and retail are steadily coming online, and demand has followed. Buyers who get in now, ahead of the suburb’s full build-out, are typically the ones who benefit most from the land value growth that follows. A 4-bedroom, 2-bathroom home in this bracket has broad appeal on both sides of the market — families wanting to upgrade into more space, and investors chasing tenants who’ll pay for size, quality, and a well-connected location. Why September 2026 Changes the Equation Most turnkey releases on the market right now are stretching into 2027 completions. This Cobblebank house and land package doesn’t ask you to wait that long. A near-term handover means less time exposed to construction-cost creep, less uncertainty sitting on your plate, and — for investors specifically — rental income starting sooner rather than later. When you’re comparing packages side by side, an earlier completion date is often the difference that actually moves the needle on returns. The Turnkey Difference Building usually means managing a dozen moving parts — land, construction, driveway, fencing, landscaping — each with its own contract, its own timeline, and its own risk of blowing out. A turnkey package collapses all of that into one fixed price, signed once, delivered as promised. No chasing trades. No mid-build cost surprises. Just a clear line from signing to keys in hand. For families, that means a moving date you can actually plan around. For investors, it means forecasting rental income without second-guessing whether the build will run on schedule or be delayed due to multiple factors. Who Should Be Looking at This Families who need four real bedrooms and don’t want to compromise on finish quality Investors prioritising a near-term completion and strong tenant demand Upgraders ready to move out of an apartment or smaller home into proper family-sized living Anyone tired of open-ended build timelines and ready for a fixed price, fixed date alternative Don’t Sit on This One With one of the earliest completion dates in our current lineup and limited allocations remaining, this Cobblebank house and land package won’t stay available for long. If the timeline and the price both work for you, now’s the time to act. 📲 WhatsApp us: Message us here 📞 Call: 1300 074 675 🌐 Visit: www.simplywealthgroup.com.au #Melbourne #FirstHomeBuyer #Investors #Australia #TurnkeyPackage #Cobblebank #PropertyInvestment
Read More »

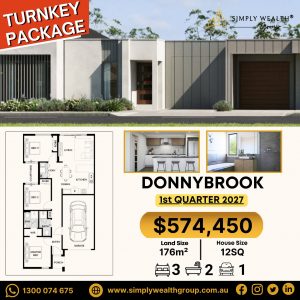
Compact House and Land Package Donnybrook — 3 Bed, $574,450

Compact House and Land Package Donnybrook — Turnkey Living, Ready Q1 2027 Looking for an affordable, low-maintenance way into property ownership or investment? This compact house and land package in Donnybrook is Simply Wealth Group’s newest turnkey release — designed specifically for first home buyers and investors who want a smart, efficient home without an oversized price tag. In a market where entry-level buyers are increasingly priced out of larger packages, this release fills a genuine gap: a fully finished, low-maintenance home at a price that keeps a first purchase realistic. Set on a 176m² block with a 12sq footprint, this is one of the most compact — and most affordable — releases in our current Donnybrook lineup. The modern facade gives it genuine street presence despite its smaller footprint, and the interior layout has been designed to make every square metre count, with no wasted space and no unnecessary extras driving up the price. Every room has a clear purpose, and the flow between kitchen, living, and bedroom zones has been kept deliberately simple so the home feels open rather than cramped, even at this size. What’s included: 3 bedrooms 2 bathrooms 1 car garage Sleek, modern kitchen Stylish bathroom finishes Practical, low-maintenance layout Priced at $574,450, this compact house and land package in Donnybrook is locked in for Q1 2027 completion — meaning the price you see today is the price you pay, with no surprise cost increases between now and handover. That kind of certainty matters, particularly for first home buyers working within a fixed budget and finance pre-approval that doesn’t leave room for unexpected cost blowouts. Why a Compact Package Makes Sense Not every buyer needs — or wants — a large, high-maintenance home. A smaller land size and house footprint means a lower purchase price, lower ongoing maintenance, and a smaller mortgage to service. For first home buyers, that translates directly into an easier path to loan approval and a more comfortable repayment schedule, without the financial strain that comes with overextending on a larger package. Lower maintenance also means more time and money left over for the things that matter, rather than being tied up in upkeep on a home that’s bigger than what’s actually needed. For investors, a compact 3-bedroom, 2-bathroom home is exactly the kind of asset that appeals to a broad tenant pool — young professionals, couples, and small families who want an affordable, well-located rental without excess space they don’t need or want to pay for. That broad appeal also tends to translate into lower vacancy rates, since the property suits a wider range of renters than a larger, more specialised home might. Why Donnybrook? Donnybrook remains one of Melbourne’s strongest-performing growth corridor suburbs, with continued investment in schools, transport, and retail infrastructure supporting long-term demand. As the suburb continues to develop, new residents are drawn by the combination of affordability and improving amenity — a mix that tends to support steady, sustained demand rather than short-term speculative interest. Buying into a maturing suburb like Donnybrook at this price point gives buyers exposure to the kind of land value growth that typically slows once an area is fully built out — meaning early entry can matter as much as the home itself. For investors and owner-occupiers alike, getting in at this stage of the suburb’s growth curve is often where the strongest long-term value sits, well before infrastructure and amenity are fully established. Why Go Turnkey? A turnkey package removes the biggest source of stress in building: coordination. Instead of managing separate contracts for land, construction, driveway, fencing, and landscaping, everything is locked into one fixed price before you sign. That protects you from rising construction costs and shifting completion dates — both real risks for buyers managing a build independently in today’s market, where trade shortages and material cost increases have made timelines increasingly unpredictable. With a turnkey package, you get keys in hand with nothing left to organise — no chasing separate trades, no juggling multiple invoices, and no ambiguity about what “complete” actually means. For first home buyers especially, that simplicity can make the difference between a stressful, drawn-out process and a straightforward path from contract to move-in day. Who This Home Suits This compact house and land package in Donnybrook is built for a wide range of buyers: First home buyers wanting a genuinely affordable entry point without compromising on quality or location Investors after a low-maintenance asset with strong, broad-based rental appeal and lower ongoing costs Downsizers who want the comfort of a modern home without a larger footprint to maintain Buyers priced out of larger packages who still want to build equity in a growth corridor suburb rather than delaying their entry into the market Secure Your Spot Allocations for this compact house and land package in Donnybrook are limited, and Q1 2027 completion slots won’t stay open for long. If affordability and location are top of your list, this is worth acting on before the next price adjustment closes the door on today’s pricing. 📲 WhatsApp us: Message us here 📞 Call: 1300 074 675 🌐 Visit: www.simplywealthgroup.com.au #Melbourne #FirstHomeBuyer #Investors #Australia #TurnkeyPackage #Donnybrook #PropertyInvestment
Read More »
Building Costs

Building Costs Are Up, Now So Is Your Rate: What First Home Buyers Need to Know

Building Costs Are Up, Now So Is Your Rate: What First Home Buyers Need to Know Borrow less than the bank offers you, as building costs in Melbourne keep climbing, and the RBA lifted the cash rate to 4.60% on 29 September, so every extra dollar of build price now costs more each month. Most buyers chase the rate headline and overlook their loan size, yet a smaller loan protects you whatever the RBA decides next. Victoria’s stamp duty exemption and the $10,000 First Home Owner Grant can soften the blow, but only if you plan around them. This guide shows what the squeeze costs and how to use those incentives before you commit. The Double Squeeze Facing First Home Owners Most buyers blame interest rates alone, and they’ve got it backwards. Builders’ prices set the size of your loan, and the cash rate sets what that loan costs you. You absorb both hits at once, so treat them as one problem and budget for both together. The data backs that up. Nationally, house construction costs rose 2% in the June quarter of 2026 and now sit 51% above pre-pandemic levels, according to the National Housing Supply and Affordability Council. A 2% rise sounds small until you stack it on top of 51%, which is why last year’s quote deserves a second look. What a 4.60% Cash Rate Does to Your Repayments The RBA lifted the cash rate by 25 basis points to 4.60% on 29 September. That’s its fourth rise of 2026 and 100 basis points since the start of the year, per Commonwealth Bank’s decision summary. The Board also left the door open to further increases, so plan for that outcome, not for hope. Lenders also test your loan at a buffer above the actual rate. So your borrowing power shrinks even when your income stays put. Ask for a fresh pre-approval before you sign anything, because an approval from six months ago no longer reflects today’s reality. Want your own numbers? Book a free property analysis with us and find out what you can borrow safely, and which Victorian incentives you qualify for, before you sign anything. Get Expert Help Choosing Your Next Property Let’s Talk Now! The Monthly Cost of a Build Blowout These figures assume a 6.5% rate over 30 years, principal and interest, so treat them as a guide. An extra $50,000 on your build adds roughly $316 a month. A 0.25-point rate rise on a $600,000 loan adds roughly $98 a month. Every month of delay keeps your rent running while interest accrues on drawn funds. Together, those hits can swallow the buffer you planned for bills and savings. Which Victorian Incentives Can First-Timers Still Claim? Victoria still gives you a real edge. The State Revenue Office exempts eligible first-home buyers from stamp duty on homes up to $600,000, reduces duty on homes up to $750,000, and covers vacant land you buy to build your first home. The $10,000 First Home Owner Grant can sit on top of that saving when you buy or build a new home, provided your contract price stays at $750,000 or less. That cap shapes your design decisions as much as your budget, so confirm it before you pick a floor plan or a design upgrade. Structure matters, because in many land-and-build deals you pay duty on the land value rather than the finished house, so the savings can run bigger than you’d expect. Confirm both concessions and your contract structure with the State Revenue Office before you sign. Your Pre-Contract Checklist Run this checklist before you commit a cent. Stress-test your repayments at a rate one percentage point above today’s. Ask for a fixed-price contract and a clear list of inclusions. Query every provisional sum, because those figures move first. Hold a contingency outside your deposit for site costs and variations. Confirm your lender’s valuation supports the contract price. Confirm your contract price sits under the $750,000 cap for the First Home Owner Grant. Why the Cheapest Quote Rarely Stays the Cheapest A low headline price looks attractive when you compare builders side by side, but it often hides allowances that the final contract quietly shifts back onto you. Builders can keep a quote sharp by listing generous provisional sums, basic inclusions and optimistic site assumptions, then adjust the figures once work begins and you have already committed your deposit. You protect yourself by comparing contracts line by line rather than total by total, which means asking each builder to confirm what the price includes, what it excludes and which items remain estimates. A slightly higher fixed price with clear inclusions usually costs you less in the end than a cheaper offer that grows with every variation. Build Your First Home Around the Next Decade Most buyers treat their first home as a single purchase, yet it works better as the first move in a longer roadmap that shapes how much you can borrow, save and invest over the following decade. When you size your loan with that horizon in mind, you leave room to build equity steadily instead of stretching to the limit on day one. A disciplined plan also gives you a clear reason to say no when a design upgrade, a larger floor plan, or a rushed deadline pushes the budget past what you can comfortably carry. Buyers who hold that line tend to keep their finances flexible, which matters when rates, wages and construction prices move in directions nobody can predict. Need Help Finding the Right Residential property? Get Your Free Consultation Discipline Beats Hype When Rates and Build Prices Rise Here’s the principle: claim every Victorian incentive you qualify for, then set your budget by what you can carry at 4.60% and above, not by what a lender approves. Walk away from any deal that only works if rates fall. Forecasters disagree on when cuts arrive, and build prices won’t wait for them. Simply Wealth Group backs everyday Australians with property

Read More »
Portfolio

The RBA’s Fourth Hike of 2026: What It Means for Your Portfolio

The RBA’s Fourth Hike of 2026: What It Means for Your Portfolio The RBA lifted the cash rate by 25 basis points to 4.60% on 29 September, its fourth hike this year and the highest rate since 2011. For you, that means tighter borrowing power, heavier holding costs and a harsher test for weak assets. Most investors panic or wait for cuts.  A resilient property investment portfolio relies on buffers, not forecasts. It’s not a reason to sell. It’s a reason to stress-test, and this guide shows you how. Will the RBA Hike Again in November? The picture shifted after the decision. August CPI came in at 4.0% year-on-year, lower than expected, and the chance of a November hike fell to around 20%, per ABC News. Then the RBA’s minutes read hawkish, and the door to a fifth hike reopened. The September-quarter CPI on 28 October now carries the most weight. The big banks still disagree. ANZ and Westpac expect a hike to 4.85% at the 3 November meeting, while CBA and NAB expect a hold, per The Adviser’s post-minutes round-up. Don’t bet your cash flow on either camp. A month before September’s hike, nearly all economists expected a hold, per investingLive. Build a plan that works at 4.60% or higher. Get Expert Help Choosing Your Next Property Let’s Talk Now! Real Cash Flow Cost of a 4.60% Cash Rate Run the numbers before you run the narrative: Repayments: the average new owner-occupier variable rate now sits near 6.5%, per Savings.com.au. Borrowing power: four hikes have trimmed about $47,000 from a single borrower’s capacity and $94,000 from a couple on average incomes. Negative gearing: it softens your tax bill, never the monthly cash outflow. Buffers: a thin offset balance turns a rate scare into a forced sale. Are You Building for Rates or for Headlines? Most investors get this backwards. They chase the highest yield, then panic when the repayment lands. Smart property investors in Australia do the opposite: they buy for long-term growth and fund each purchase for the worst-case rate. Discipline looks boring until a cycle like this arrives, and then it looks smart. Hype says rates will fall next year, so stretch now. A roadmap says hold the asset, protect your serviceability and let compounding do the heavy lifting. Location, undersupply and rental demand matter far more than any single RBA meeting. Short-term noise rarely wrecks a long-term plan, but poor structure often does. Not sure how your numbers hold up at 4.60%? Book a free property analysis with Simply Wealth Group and get a straight answer.  Will the RBA Hike Again Before Christmas? Economists disagree, as before the decision, 26 of 31 surveyed expected the cash rate to sit at 4.60% through December, while ANZ tipped 4.85%, per investingLive’s poll. The median forecast sees 4.35% by the end of 2027, though views split widely from the third quarter of that year. That spread tells you how uncertain this is. Don’t bet your cash flow on any of those calls. A month before this hike, nearly all economists expected the RBA to hold. Forecasters missed the turn, so don’t build your plan on their next guess. Build one that works if the rate stays at 4.60% or climbs further. That’s discipline, not pessimism. Repayment Pressure If Rates Keep Climbing Run a simple example: on a $600,000 loan, each 25-basis-point rise adds roughly $1,500 a year in interest, or about $125 a month. Four hikes mean around $6,000 extra a year, or $500 a month. That’s our own interest-only calculation, so check it against your actual loan terms. Run yours today. Now multiply that across every loan you hold, and two or three properties turn a small rate move into a serious cash-flow gap. Disciplined investors know that number before the bank’s letter arrives. Most others learn it the hard way, usually while selling a good asset at the wrong time. Don’t be that investor. Actions Disciplined Investors Should Follow Currently Experienced property advisors in Australia will tell you the same thing in a hiking cycle: fix the plumbing before you chase the next deal. Stress-test every loan at one percentage point above today’s rate. Hold several months of holding costs in offset. Ask your broker whether your loans still compete. Pause new purchases unless the numbers survive the stress-test. Learn the numbers first, then make the next decision. Need Help Finding the Right Residential property? Get Your Free Consultation Holding Quality Assets Matters More Than Timing the Market Rate cycles tempt you to play trader. Investors sell after a hike, then try to buy back before the next cut, and they usually miss both moves. Every transaction costs you stamp duty, agent fees and months of lost rent. Quality assets in undersupplied locations reward patience far more reliably than any well-timed exit. Compounding needs time, and time needs a funding plan that survives pressure. Ask yourself three things: can the property carry itself at a higher rate, does the location attract steady tenants, and will you still hold it in ten years? If you answer yes to all three, a hiking cycle is just noise. Keep your eyes on the roadmap, not the headline. Discipline Beats Forecasts: Your Move After the Fourth Hike The fourth hike changes the maths, not the principles. Rates rise and fall, but a well-structured plan holds through both. Run your stress-test this week, rebuild your buffer and hold quality assets for the long term. Anyone who sells in panic usually sells to someone who prepared, so be the one who prepared. Simply Wealth Group helps everyday Australians build high-performing property portfolios through advisory, portfolio management, mortgage solutions and education. Our team are full-time property investors, so we explain the numbers the way we live them. We won’t sugarcoat the numbers, and we won’t sell you hype.  Take the next step, and call us for your free property analysis today. FAQs: How do you stress-test a purchase after four hikes? Start with

Read More »
Cash Rate

Cash Rate Hits 4.60% — Here’s What That Adds to Your First Home

Cash Rate Hits 4.60% — Here’s What That Adds to Your First Home The RBA lifted the cash rate to 4.60% on 29 September, its fourth hike this year and the highest level since 2011. For first-home buyers, that adds about $113 a month on an average $731,000 loan, per Money magazine. It’s a heavy hit for anyone planning to build. But repayments are only half the bill. Most buyers obsess over the rate and ignore the build quote, yet house construction prices rose 5.9% over the year to June, per the ABS. Here’s the full cost, and how to plan around it before you sign. What Has the RBA Actually Done to Your Repayments? Four hikes since February have lifted the cash rate from 3.60% to 4.60%, per the RBA. That’s 100 basis points in eight months, a pace few buyers budgeted for. Lenders typically pass these rises on to variable loans, so your monthly repayments climb even though your income hasn’t moved. Don’t bank on relief soon. The RBA says it will lift rates again if needed, and ANZ is the only major bank pricing another hike in November. The next RBA meeting lands on 3 November. Plan around the rate you can afford, not the cut you’re hoping for. How Hard Are Building Costs Hitting a New Home? ABS data shows house construction prices rose 5.9% over the year to June 2026, the biggest annual jump since mid-2023, on a $500,000 build quote, which adds roughly $29,500. Materials grab the headlines, but scarce trades are the real handbrake on delivery times. Every idle month costs you rent and interest on progress payments, long before the keys arrive. Rising building costs in Australia also stack on top of higher borrowing costs, and the two feed each other. That’s why a build that looked affordable in January can look stretched by October. Want your build budget stress-tested at 4.60%? Book a free property analysis with Simply Wealth Group and see where your numbers really stand. Where Is the Extra Money Actually Landing? Watch these five pressure points: Higher monthly repayments from four hikes in 2026 Build price growth lifting your final quote Interest on construction progress payments Rent while delays push back handover A contingency buffer that 3% no longer covers Is Waiting Really the Safer Play? Most buyers get this backward, as they wait for rates to fall and assume the build quote will sit still. It won’t. Building construction prices rose 1.0% in the March quarter, driven by houses, then house construction jumped another 2.0% in June, per the ABS. Waiting isn’t a strategy. It’s a bet. Meanwhile, investors and owner-occupiers compete for the same builders, trades and house-and-land stock, and waiting hands them first pick. Don’t chase the market, though. Stress-test your repayments at 4.85%, one more quarter-point hike than today, add a proper buffer, and move only if the numbers still hold. What Should You Lock In Before the Next RBA Meeting? A fixed-price build contract, signed before further rises flow through A contingency of 10% of build cost, not 3% A builder with a verifiable delivery history, not the cheapest quote Repayments tested at 4.85%, not just today’s rate Finance pre-approval checked against current rates How Much Should You Borrow While Rates Keep Climbing? Most buyers borrow what the bank offers, and that’s a mistake. A lender’s maximum tells you what it’s willing to risk, not what you can live with. Work backward from a comfortable monthly repayment at 4.85%, then let that number set your budget. Keep spare cash after repayments, because build delays and surprise extras never arrive on schedule. If your plan only works at the top of your borrowing range, shrink the plan, not the buffer. Is a Turnkey House-and-Land Package Safer Right Now? A turnkey package bundles land and build under one contract, so you know the full price upfront. That certainty carries real value while construction prices keep rising. It also gives you one contract to read instead of several. Certainty isn’t automatic, though. Check the inclusions line by line, confirm what sits outside the price, and test the builder’s delivery record. A cheap package with thin inclusions simply moves the blowout to after handover. The Bottom Line: A 4.60% Cash Rate Rewards Discipline, Not Timing A 4.60% cash rate costs you every month, and rising build prices cost you before you collect the keys. Neither justifies panic. Both demand proper numbers, a real buffer, and a refusal to back any plan that only works if rates fall. Buy with discipline, build with a cushion, and treat every optimistic forecast as a bonus rather than a plan. Simply Wealth Group is a team of full-time property investors who give straight answers, not hype. Whether you’re buying your first place or sitting alongside property investors in Melbourne, our property strategy, mortgage solutions and project management keep your numbers honest. Your numbers get tested by people who invest for a living, not by a script. Start with a free property analysis at Simply Wealth Group. Ready to see what 4.60% really means for your build? Call us or book your free property analysis today. FAQs: How much contingency should I budget on a new build? Aim for 10% of total build cost, not the old 3%. At today’s rates, one supplier increase or trade delay can wreck a thin buffer. A bigger cushion also stops you scrambling for extra finance mid-build. What does a fixed-price contract actually protect me from? It protects you from cost rises after you sign, not before. Builders price expected increases into quotes, so signing early beats signing late. Ask your builder exactly what the contract excludes before you sign. How do I stress-test my repayments for another hike? Add 0.25 to 0.50 percentage points to your loan rate and check you still cover repayments comfortably. Use the Mortgage Repayment Calculator on our website to run it. Do it before you sign, not after, so

Read More »
migration growth in Australia

Migration Is Outpacing New Builds — Here’s What That Means for Investors

Migration Is Outpacing New Builds — Here’s What That Means for Investors Most investors read the shortage headlines and hear “guaranteed win”. They’ve got it backwards. Even after easing, migration growth in Australia still added 292,100 people in the year to March 2026 (per the ABS), while building trails was the national target. The short answer: the supply gap props up rents and long-term demand, but it won’t rescue a badly bought property.  With the RBA cash rate now at 4.60%, discipline beats the story every time. Smart investors treat the gap as a chance to buy carefully, not rush. This post shows where demand lands first, why approvals mislead, and how to build a portfolio that survives higher rates. How Big Is the Gap Between Migration and Supply? The ABS puts population growth at 392,700 people in the year to March 2026. Net overseas migration supplied 292,100 of them, down from 309,500 the year before. That’s cooler, but it’s still a heavy load for a housing system that isn’t building fast enough to house new arrivals and existing households alike. Demand keeps arriving whether construction is ready or not. The supply side looks worse, as the National Housing Accord targets 1.2 million homes between July 2024 and June 2029. Government advisers now expect it to land around the end of 2030, according to the ABC, and Master Builders forecasts a 204,000-home shortfall. That’s a gap of years, not months, and no single policy announcement closes it quickly. Where Does Migrant Demand Show Up First? In rentals, as newly arrived residents typically rent before they buy, Cotality’s June quarter data shows national rents up 5.9% over the year. Vacancy sits at 1.6%, with every capital below 2%. Tenants compete for scarce listings, and landlords with well-located properties benefit from that pressure through higher, more reliable income. That’s the real engine behind the shortage story. That income only holds if someone manages it properly. A strong property management service in Australia screens tenants, prices rent to the market and keeps vacancy short, because empty weeks quietly wreck cash flow. Simply Wealth’s specialists do exactly that, and each proposed investment comes with a rental guarantee, which takes pressure off new investors. Get Expert Help Choosing Your Next Property Let’s Talk Now! Why Don’t Approvals Solve the Shortage? Approvals make good headlines, but nobody lives in an approval. The ABS recorded 17,687 dwellings approved in July, a 3.6% monthly fall, though still 9.0% above a year earlier. Treat that number as a signal of intent rather than delivery, because approved projects still need finance, labour and materials before anyone gets keys. Approvals are the starting gun, not the finish line. Higher rates squeeze builders and developers as well as buyers, and the RBA lifted the cash rate to 4.60% on 29 September, its fourth rise this year. If you’re planning a build rather than buying established, read our guide on what rates at a 15-year high mean for your build budget. Approvals lead, completions lag, and the shortage lives in that lag, which keeps pressure on rents. What Do Most Investors Get Wrong? Most investors chase the shortage story. Disciplined ones check these four things first: Treating a national shortage as a local guarantee: A weak location stays weak in a tight market. Ignoring holding costs: If a property only works when rates fall, it isn’t a strategy. Chasing the headline suburb: Crowded postcodes inflate entry prices and squeeze your yield. Skipping the roadmap: One purchase isn’t a portfolio, and sequence matters. Not sure your next purchase passes the numbers test? Book a free property analysis with Simply Wealth Group and get a straight answer before you commit. Investing Through the Gap Build for the long run, not the news cycle: Buy for cash flow you can carry today, then stress-test it against higher rates. Choose areas with jobs, transport and proven rental demand, not just a low entry price. Plan your next three purchases, not only the first. Keep a cash buffer for vacancy and repairs. The Shortage Is Real, but Discipline Still Pays Here’s the takeaway. Net overseas migration and slow construction give Australian property a solid demand floor, but a floor isn’t a return. Buy well, hold comfortably, and build a roadmap you can follow when the headlines change. Investors who set rules early and stick to them through rate rises are usually the ones still holding quality assets years later.   Simply Wealth Group is a property investment group in Australia built around full-time property investors with proven results who value personal sense, not just financial sense. Its team covers property advisory, mortgage solutions, portfolio management and education under one roof, so your strategy stays joined up from first purchase to the next.  Ready to build your roadmap? Book a free property analysis today. Need Help Finding the Right Residential property? Get Your Free Consultation FAQs: Will slow supply guarantee my property grows in value? No, as a shortage lifts demand broadly, but location, purchase price and holding costs decide your result. Weak areas stay weak in a tight market, and overpaying for a strong area still drags on returns. Check local demand before assuming the national story fits your street. How should I stress-test a purchase at 4.60%? Run the numbers at a cash rate one to two points higher and confirm you can still carry the loan comfortably. If a deal only works when rates fall, walk away. Keep a buffer for vacancy and repairs, because a plan with no room for surprises isn’t a plan. Is a rental guarantee enough protection against vacancy? It helps, but read the terms before you sign. Vacancy is an average, and your property sits on one street. Ask what the guarantee covers, how long it lasts and what happens when it ends, then judge the property on its own rental merits. Should I buy new or established in a supply-short market? New builds add supply and can carry depreciation

Read More »
Interest Rates

Rates at a 15-Year High: What It Means for Your Build Budget

Rates at a 15-Year High: What It Means for Your Build Budget The RBA lifted the cash rate to 4.60% on 29 September, its highest level in 15 years. For first home buyers planning a build, that’s a double hit: less borrowing power and a bigger price tag. Most people only notice the repayment, but the bank looks at your borrowing limit first. The short answer is that the higher interest rates shrink your loan, construction prices keep climbing, and your budget needs a real buffer. Most buyers plan around the builder’s quote. Plan around the rate instead, and aim for a budget that still works if the RBA lifts rates again. Why Does This Rate Rise Hit Harder Than the Headline Suggests? The Monetary Policy Board lifted the cash rate by 25 basis points on 29 September. It’s the fourth hike of 2026, so borrowers now face a full percentage point more than they did in January. That’s not a rounding error. For anyone with a loan, it flows straight into monthly repayments, and for anyone applying, it flows straight into the borrowing limit. The Board also kept the door open to further increases, pointing to stubborn inflation and higher energy prices. Most buyers treat that as a repayment problem. It’s a borrowing-power problem first, because the bank sets your limit long before you see a single repayment, and that limit decides how much house you can actually build. Get Expert Help Choosing Your Next Property Let’s Talk Now! Where Does the Extra Money Actually Go Each Month? Run the numbers, as on a $600,000 loan over 30 years, moving from a 6% rate to 7% adds about $394 a month in principal-and-interest repayments. That’s our own calculation using round example rates, so check your actual loan, but the scale is the point. Four hikes of 25 basis points this year add up to exactly that one percentage point. Lenders also assess you at a buffer above the actual rate, so your borrowing limit drops faster than your repayments rise. That’s the part most first-time builders get backwards. They fixate on whether they can afford the repayment today, when the real q67uestion is whether the lender will approve the loan they need at all. Construction Prices Are Still Running Hot Building costs in Australia keep rising, with ABS data showing house construction prices jumped 5.9% over the year to June 2026, the biggest annual rise since June 2023. That’s no one-off blip. The RBA also notes that firms are passing higher fuel and other costs on to customers. The June quarter alone rose 2.0%, the largest jump since September 2022, and the ABS flagged conflict-related shipping delays (same ABS source). Assume your builder has already priced part of the next rise into your quote. A fixed price protects you after you sign, not before, so the timing of that signature matters more than most buyers realise. Your budget only works if it survives the next rate rise. Book a free property analysis with Simply Wealth Group before you sign anything. Is a Fixed Price Really the Safety Net Builders Promise? It protects you from movements after signing, and that’s valuable when materials and labour are both under pressure. A fixed price turns an open-ended risk into a known number, which is exactly what a lender wants to see when it assesses your construction loan. But read the fine print on what counts as a variation, because the exclusions are where budgets leak. Delays are the other half of the story. A fixed price can’t buy you a bricklayer, and every month the site sits idle adds interest and rent on your side of the ledger. Choose a builder with a verifiable delivery history, and ask to see recent projects finished on time, not just the cheapest quote on the table. Need Help Finding the Right Residential property? Get Your Free Consultation What Does a Disciplined Build Budget Look Like? Build your numbers around these rules: Test your loan at one to two percentage points above today’s rate, not at the current one. Hold a 10% contingency, not 3%, because one supplier increase can erase a thin cushion. Price the delay, since interest and rent keep running while the slab waits. Compare builders on delivery history and contract terms, not just the lowest quote. Get your finance reassessed before you sign the contract, not after. Where Do Most First-Time Builders Go Wrong? Most blown budgets trace back to a handful of avoidable errors: Budgeting off last year’s quotes, when house construction prices have moved almost 6% since. Treating pre-approval as a promise when it’s only a snapshot of your position on one day. Forgetting site costs, driveways, fencing and landscaping that sit outside the base price. Running the build with nobody holding the builder and trades to the timeline. Build Your Budget for Higher Rates, Not Hopeful Ones Rates at a 15-year high won’t sink your build. A thin budget will. Test every number at a higher rate, and if the plan only works at today’s rate, rework it before you sign. That’s discipline, and it beats hype every time. This is where good property investment advisors earn their fee: they pressure-test your numbers while you still have options. Simply Wealth Group helps everyday Australians build property portfolios with a numbers-first, no-hype approach. Our services cover education, mortgage solutions, property advisory and project management, plus Melbourne house-and-land packages. Our team are full-time property investors, so you get guidance from people who live the strategy. Explore our services at Simply Wealth Group. Want to see what your build really costs at 4.60% and beyond? Book your free property analysis with us or call us today. FAQs: Why does a construction loan behave differently from a standard home loan? Lenders release the money in stages as each build milestone is completed, so you typically pay interest only on what you’ve drawn. A rate rise mid-build still hits you before the house

Read More »
property

Locking In Today’s Price: Why Timing Matters More Than Ever in This Market

Locking In Today’s Price: Why Timing Matters More Than Ever in This Market Most investors get timing backward, as they wait for established prices to fall, then watch building costs rise. Timing matters more than ever because the market is splitting: Melbourne values are softening, yet the ABS says new dwelling prices rose 5.7% in the year to July 2026. Any property investment firm in Melbourne worth trusting will tell you to plan, not predict. That does not mean rushing in, as a locked price guarantees no growth, and it never replaces solid strategy. It removes one specific risk: paying more later for the same home. Nobody should buy on fear, but everybody should understand what a delay actually costs them. Is the Market Really Falling Everywhere? Not quite, as Melbourne dwelling values fell 1.1% in August and now sit about 6% below their November 2025 peak, per Cotality. Nationally, values have slipped five months in a row. Across the capitals, 93% of suburbs recorded a fall through winter. Established buyers have room to negotiate. Most commentary stops there. New homes tell a different story. The ABS says builders raised base prices to pass on higher labour and material costs. Run that 5.7% over a $700,000 package, and you get about $39,900 a year, or roughly $3,300 a month. Land does not always move in step with build costs, so treat that as an illustration, not a forecast. Get Expert Help Choosing Your Next Property Let’s Talk Now! What Is the Real Price of Waiting? The brochure price is only part of the bill, and most buyers discover the rest too late. Delay does not just raise the sticker price. It quietly stacks extra costs on top, and each one lands in your pocket rather than the builder’s. Four pressures matter most: Escalation clauses: builders increasingly write them in, so today’s quote may not be your final price. Valuation gaps: if costs outrun the bank’s valuation, you cover the difference in cash. Borrowing capacity: three RBA hikes this year lifted the cash rate to 4.35%, and each further rise trims what lenders offer. Holding costs: delays leave you paying rent and a mortgage at the same time. Who Do the New Tax Rules Actually Favour? Parliament passed the changes in June. From 1 July 2027, rental losses on established homes bought after 7:30 pm on 12 May 2026 can’t offset your salary. New builds keep negative gearing. The 50% CGT discount is replaced by indexation and a 30% minimum tax on gains. Source Canberra designed that carve-out to steer investment toward new supply, which favours house and land packages in Melbourne over established stock. Not every new build qualifies, though. Knock-down rebuilds do not, so confirm eligibility with your accountant before you sign, and read the fine print on any project you consider. Want to see what a locked-in price looks like for your numbers? Book a free property analysis with Simply Wealth Group. Is There a Disciplined Way to Lock In Your Price? Yes, and it looks nothing like panic buying. Discipline means a checklist, not a countdown clock. You refuse any deal that only works if everything goes right, and you test every assumption before you sign. Work through these four steps in order: Fix your finance first: test your borrowing capacity at higher rates before you look at any lot. Price the whole project: land, build and site costs each carry their own risk, so add them together. Scrutinise the contract: provisional sums can blow out, so ask what stays fixed. Stress-test your cash flow: run repayments one percentage point above today’s rate, and proceed only if the numbers hold. Need Help Finding the Right Residential property? Get Your Free Consultation Can You Afford to Wait for the RBA? You can try, but you are betting on something nobody controls. Markets expect the RBA to lift the cash rate again at its 29 September meeting, and the ABS puts annual inflation at 4.60% for July. Even if the RBA pauses afterwards, the board says it remains focused on preventing high inflation from becoming entrenched. You can refinance a loan when rates ease, as you cannot go back and buy at last quarter’s price. Waiting feels safe, but it is still a decision, and it carries a cost. Disciplined investors rarely wait for perfect conditions. They set a strategy, protect what they can control, and let time do the compounding. Price You Lock In Is the Only One You Control Nobody rings a bell at the bottom of a cycle. Rates, values and tax settings will keep moving, and property investors in Melbourne who wait for certainty usually end up paying for it. The build price in your signed contract is the one number you can fix today, while everything else stays open. The principle is simple: protect the cost you can control, stress-test the rest, and hold for the long term. That is a roadmap, not a rush. Set it once, review it yearly, and resist every headline that tells you to abandon it. Simply Wealth Group helps everyday Australians build high-performing property portfolios. Our Melbourne-based team invests full-time and guides you every step, from property strategy to mortgage solutions and project management. Explore more at https://simplywealthgroup.com.au/. Ready to lock in your price? Book your free property analysis or call us today. FAQs: How does Simply Wealth Group approach a first purchase? We put strategy and finance ahead of stock. Your finance broker and wealth strategist matter more than any one property, and our team invests full-time, so the numbers must work first. That reflects our view that ethical advice gives you more than just numbers to decide on. Why do values fall while build costs rise? Established values follow borrowing capacity and rates. Build costs follow labour and materials, which builders pass on, while infrastructure and energy projects compete for skilled trades. That is why cheaper established stock and dearer new builds can sit side

Read More »
eofy 2026 for property

2026 Property Investor Guide: The Ultimate Income and Deduction Playbook

2026 Property Investor Guide: The Ultimate Income and Deduction Playbook Introduction In 2026, the ATO is no longer relying on what you report. It is actively checking it. With expanded data matching across rental bond authorities, property managers, and short term platforms like Airbnb and Stayz, property investors are under closer scrutiny than ever. Many investors are not audited because they intentionally do the wrong thing, but because they misunderstand what needs to be declared and what can actually be claimed. The rules have also become more complex. Draft guidance such as TR 2025/D1 signals how the ATO is tightening its position on private use, holiday homes, and lifestyle properties. At the same time, common mistakes around loan interest, repairs, and depreciation continue to trigger adjustments and penalties. This guide breaks down the key areas of your rental property tax return based on the ATO’s Rental Property Statement. It will help you understand what must be declared as income, what you can legitimately claim as deductions, and where investors most commonly get it wrong. I. What You Must Declare (Assessable Income) One of the most common mistakes investors make is declaring only the net rent they receive. The ATO requires you to declare gross income before any fees or deductions. Gross RentYou must include every dollar paid by a tenant or guest. This includes weekly rent, short term accommodation income, and any cleaning or service fees charged through platforms like Airbnb or Stayz.Example: If your agent deducts $3,000 in fees and sends you $27,000, you must still declare $30,000. Bond Money RetainedIf you keep part or all of a tenant’s bond to cover unpaid rent or damage, that amount is treated as income. Insurance PayoutsIf you receive insurance for loss of rent, it must be declared as income. Payments for property damage are treated differently and may fall under capital gains rules. ReimbursementsIf a tenant reimburses you for a cost you have already claimed as a deduction, such as a repair or water bill, that reimbursement must be declared as income. Discounted Rent to Family or FriendsYou must still declare the income received. If the rent is below market value, your deductions may be limited to the amount of income earned. II. Expense Details: Maximising Your Deductions The Green Zone (Immediate Deductions) These are expenses you can generally claim in full in the same financial year. Advertising and CommissionsYou can claim agent fees, platform commissions, and listing costs.You cannot claim the value of your own time managing the property. RepairsRepairs relate to fixing something that is broken or damaged.Examples include repairing a leaking tap, replacing a broken window, or fixing storm damage. What you cannot claim here are initial repairs. If the damage existed when you purchased the property, the cost is considered capital in nature. A simple rule: if the work improves or replaces the whole asset rather than fixing damage, it is likely capital. Operational CostsCleaning, gardening, and pest control costs are deductible when incurred during rental periods. The Amber Zone (Holding Costs and Apportionment) These expenses are often deductible, but may need to be apportioned. Interest on LoansYou can claim interest on the portion of the loan used for the investment property.You cannot claim interest on funds used for personal purposes such as holidays, cars, or private expenses. Example: If you redraw from your mortgage for personal use, you must separate and exclude that portion of interest. Rates and TaxesCouncil rates, water rates, and land tax are generally deductible.You cannot claim water usage charges that are paid directly by the tenant. InsuranceLandlord, building, and contents insurance are deductible.Personal insurance such as life, trauma, or income protection is not. Apportionment RulesIf the property is used privately or is not genuinely available for rent, expenses must be apportioned.This includes: Private stays by the owner Periods where the property is not actively listed for rent Renting below market value III. Claiming Over Time Not all expenses can be claimed immediately. Some must be claimed over several years. Building Write Off (Capital Works)Most residential properties allow a deduction of 2.5 percent per year over 40 years.Eligible build to rent developments may qualify for an accelerated 4 percent rate. Depreciation (Plant and Equipment)Assets such as appliances, carpets, blinds, air conditioning units, and hot water systems are depreciated over their effective life.This is a key area many investors miss or underclaim. RenovationsMajor upgrades such as new kitchens, bathrooms, or extensions are capital works and must be depreciated over time.They should not be claimed as repairs. Instant Asset Write OffThis may apply only if you are genuinely carrying on a rental property business, which is uncommon and depends on your circumstances.Most individual investors will not qualify and will instead claim depreciation over time. IV. The Absolute No List (Common Audit Triggers) Travel ExpensesTravel costs related to inspecting or maintaining a residential rental property are not deductible. This includes flights, fuel, and accommodation. Borrowing Costs Over $100Expenses such as loan establishment fees and lender’s mortgage insurance must be spread over five years. The Leisure Facility Risk (TR 2025/D1)If you use a holiday home privately during peak periods such as Christmas or Easter, the ATO may classify it as a lifestyle asset. The consequence can be severe. The ATO may deny key deductions such as interest, rates, and land tax for the entire year. Keeping accurate records of private use is essential. Investor Action Checklist for 2026 Declare gross income, not net amounts received Review loan redraws and separate personal use Ensure ownership percentages match your tax return Keep a clear record of any private use Confirm your depreciation schedule is up to date Final Word Property investment offers strong tax advantages, but only when structured and reported correctly. Most costly mistakes are not aggressive claims, but simple misunderstandings that compound over time. Getting it right can mean the difference between maximising your return and triggering an ATO review. Need Help Getting This Right? If you are not completely confident your property is structured correctly

Read More »
Melbourne Buyers Window

Unlocking the Window: Why the April 2026 Cotality Report is a Game-Changer for Melbourne Buyers

Melbourne Housing: Why the “Buyer’s Friend” is 2026’s Best Kept Secret If you’ve been on the fence about the Melbourne property market, the latest Cotality Monthly Housing Chart Pack (April 2026) has a clear message: the window of opportunity you’ve been waiting for is officially open. While other capital cities are hitting record-breaking highs, Melbourne is moving to a different beat—one that favors the prepared buyer. Here is why the latest data suggests that “waiting for a better time” might actually be your biggest risk. 1. The “Buyer’s Friend” Advantage While the national market grew by 2.1% last quarter, Melbourne was the only major capital to see a meaningful cooling, with values dipping -0.6%. In a country where Perth and Brisbane are soaring at double-digit annual growth, Melbourne’s relative “cool” is a rare gift for buyers. Below the Peak: Melbourne values are currently -1.3% below the record high seen in March 2022. Negotiating Room: With quarterly values softening, the frantic “fear of missing out” has been replaced by a market where buyers have more leverage at the negotiating table. 2. The “Move-Up” Window is Open The Cotality report highlights a significant “stratified” trend in Melbourne. The “cooling” isn’t happening equally across the board, which creates a unique strategy for those looking to upgrade: The Premium Dip: The most expensive 25% of Melbourne homes saw the sharpest decline, dropping -1.6% in value this quarter. Middle-Market Stability: The middle 50% of the market remained completely flat at 0.0%. The Strategy: If you own a mid-tier home and want to upgrade to a premium property, the “price gap” between the two has narrowed. Your current home is holding its value while your “dream” home just got a little more accessible. 3. The Hidden Cost of Staying on the Fence Many people stay on the fence to “save more,” but the Cotality data shows that the rental market is making that a losing game. Rents are Accelerating: Melbourne rents rose 4.4% over the past year. No Place to Hide: The vacancy rate is a razor-thin 1.6%, meaning competition for rentals is often as fierce as the buying market. The Math: With rental yields sitting at 3.7%, every month you wait is a month you are paying down a landlord’s equity rather than your own. 4. Why Melbourne is Different: The Supply Factor The “Chart of the Month” in the Cotality report explains why Melbourne hasn’t exploded like Perth or Brisbane. Historically, Victoria has built more housing relative to its population growth than any other state, accounting for roughly one-third of all national completions. This healthy supply-demand balance is exactly what makes Melbourne a “Buyer’s Friend”—you have more choices and less of the frantic supply-starved competition seen elsewhere. The Verdict: Strategic Timing Yes, the RBA lifted the cash rate to 4.1% in March. Yes, borrowing capacity is tighter. But the April 2026 Cotality report makes one thing clear: Melbourne is the only major market offering buyers a genuine “breather”. History shows these cooling phases don’t last forever. Once the trend turns positive again, the window of opportunity becomes much smaller—and often more expensive. What This Means for You The opportunity is there—but the real question is: what does this actually look like for you? Everyone’s situation is different. Your income, savings, borrowing power, and goals all play a part in what you can realistically do right now. And this is where most people get stuck. They understand the market is shifting, but they’re not quite sure what their next step should be. Not sure if you can actually buy yet? Let’s find out. Have a quick, no-pressure chat with us and we’ll walk you through: What you could realistically afford What options are available to you right now What your next step could look like So instead of guessing, you’ll have a clear idea of where you stand after speaking with our team. [Check Your Buying Position]

Read More »