Property Investing Advice and Market Insights.

Manor Lakes House and Land Package — 4 Bed, $694,562

Manor Lakes House and Land Package — 4 Bed, $694,562

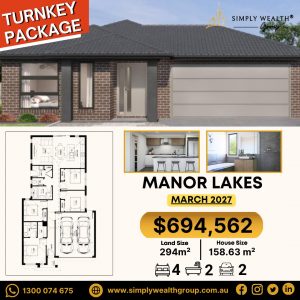
Manor Lakes House and Land Package — Turnkey Family Living, Ready March 2027 Looking for a home with real space for a growing family, without the stress of managing a build yourself? The Manor Lakes house and land package is Simply Wealth Group’s latest turnkey release — a fixed-price, fixed-timeline home designed for families and investors who want certainty from contract through to completion, without the usual guesswork that comes with building. Set on a 294m² block with a 158.63m² footprint, this design makes the most of every corner. A classic brick facade with a modern garage gives this home strong street presence, while the interior layout is built around comfort and everyday practicality — open-plan kitchen and dining, a separate lounge, and four well-proportioned bedrooms spread across a smart floorplan that balances family living with private retreat spaces. The layout has clearly been designed with real household routines in mind, separating quiet bedroom zones from the busier living and entertaining areas at the front of the home. What’s included: 4 bedrooms 2 bathrooms 2 car garage Open-plan kitchen and dining Separate lounge and living zones Modern brick facade with contemporary finishes Priced at $694,562, this Manor Lakes house and land package is locked in for March 2027 completion — meaning the price you see today is the price you pay, with no hidden extras and no surprise cost blowouts along the way. That kind of certainty is increasingly rare in a building market where prices have shifted considerably over recent years. Why Manor Lakes? Manor Lakes has established itself as one of Melbourne’s most sought-after western growth corridor suburbs, known for its established amenities, schools, parklands, and easy access to major transport routes. Unlike newer release areas still waiting on infrastructure, Manor Lakes already has much of that groundwork in place — town centres, shopping precincts, medical facilities, and community spaces are already up and running, which makes it a particularly attractive option for families who want convenience from day one and for investors who want strong, immediate rental appeal rather than waiting years for a suburb to mature around them. A 4-bedroom, 2-bathroom, 2-car home in this configuration is consistently sought after in this pocket of Melbourne’s west, appealing to both families upgrading from smaller homes or apartments and investors targeting long-term tenants who value space, established infrastructure, and proximity to schools and shops. Why Go Turnkey? A turnkey package takes the guesswork out of building. Instead of juggling separate quotes and contracts for land, construction, driveway, fencing, and landscaping, everything is bundled into a single fixed price locked in before you sign. That protects you against rising construction costs and shifting timelines — a real risk in today’s building industry, where delays and cost overruns have become increasingly common for buyers managing a build independently. For investors, that predictability means being able to plan rental income with confidence, knowing exactly when the property will be ready to lease. For families, it means knowing exactly when moving day will arrive, without the anxiety of open-ended construction delays disrupting school enrolments, lease timing, or other major life plans tied to a settlement date. Who This Home Suits This Manor Lakes house and land package has been designed with a wide range of buyers in mind: Growing families needing four genuine bedrooms and a double garage, not a compromise layout Investors after strong rental appeal in an established, amenity-rich suburb with proven tenant demand Upgraders moving from an apartment or townhouse into a full-sized family home with real separation between living and sleeping zones Buyers who value certainty — a fixed price and a fixed March 2027 completion date, without construction-cost surprises along the way Secure This Manor Lakes Package Allocations for this release are limited, and March 2027 completion slots are filling quickly. If you’ve been searching for a well-located, established-suburb package with genuine family appeal and none of the usual build-related stress, this is worth acting on before the next price adjustment locks you out of today’s price. 📲 WhatsApp us: Message us here 📞 Call: 1300 074 675 🌐 Visit: www.simplywealthgroup.com.au
Read More »
Donnybrook House and Land Package — Titled, $718,900

Donnybrook House and Land Package — Titled, $718,900

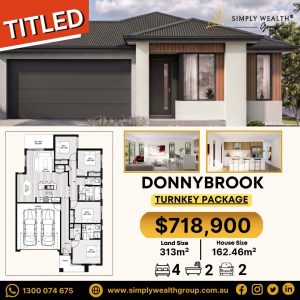
Donnybrook House and Land Package — Titled and Ready Now Looking for a spacious family home you can move into without the wait? The Donnybrook house and land package is a fully titled turnkey release from Simply Wealth Group — meaning the land is registered, the build is complete, and settlement can happen fast. No construction timelines, no uncertainty about final costs, and no lengthy back-and-forth with builders — just a ready-to-move-in home available right now, without the delays that so often frustrate buyers in today’s market. Set on a generous 313m² block with a 162.46m² footprint, this design is built for growing families who need real space to spread out. A wide double garage, four genuine bedrooms, and open-plan living give this home the kind of everyday practicality that’s hard to find at this price point in Melbourne’s northern corridor. The layout has been thoughtfully designed so that living, meals, and kitchen zones flow together, while bedrooms are positioned for privacy and separation — ideal for families with teenagers, multi-generational households, or anyone who simply values their own space. What’s included: 4 bedrooms 2 bathrooms 2 car garage Open-plan kitchen, living, and meals zones Modern facade with timber-look accents Private entertainer’s patio Priced at $718,900, this Donnybrook house and land package is titled and available now — a genuine point of difference from off-the-plan packages where buyers wait years for completion. Why “Titled” Matters A titled property means the land has already been registered and the home has been fully constructed — there’s no waiting on subdivision approvals, no construction delays, and no uncertainty about final costs. For buyers, that means finance and settlement can move quickly, often within weeks rather than years. For investors, it means the property can start generating rental income almost immediately, rather than sitting vacant through an 18–24 month build cycle. In a market where construction costs and timelines have shifted considerably, a titled property removes nearly all of that risk in one move, giving buyers far greater certainty from contract to keys. Why Donnybrook? Donnybrook continues to be one of Melbourne’s standout growth corridor suburbs, with ongoing investment in schools, transport, and retail infrastructure supporting long-term demand. As the surrounding area matures, buyers who secure property here now are positioning themselves ahead of much of that infrastructure rollout. A 4-bedroom, 2-bathroom, 2-car home in this configuration appeals to a wide pool of both owner-occupiers and tenants — families wanting room to grow, and investors chasing strong rental demand in an established, well-connected pocket of Melbourne’s north. Who This Home Suits This Donnybrook house and land package has broad appeal across different buyer types: Growing families who need four real bedrooms and a double garage, not a compromise layout Investors wanting immediate rental income without a construction wait Buyers relocating who need a fast settlement rather than a long build timeline Upgraders moving from an apartment or smaller home into something with genuine space First-time landlords looking for a low-risk entry into property investment with rental demand already established Because the property is titled, all of these buyer types can move faster than they could with a standard off-the-plan package — a real advantage in a market where timing often matters as much as price, and where delays can mean missing out on the right loan terms or rental conditions. Secure This Titled Package Titled properties move quickly, and this Donnybrook house and land package won’t stay on the market long. If you’ve been waiting for a ready-now home with real space and a fixed price, this is worth acting on today before it’s gone. 📲 WhatsApp us: Message us here 📞 Call: 1300 074 675 🌐 Visit: www.simplywealthgroup.com.au
Read More »
Beveridge House and Land Package — 4 Bed, $679,400

Beveridge House and Land Package — 4 Bed, $679,400

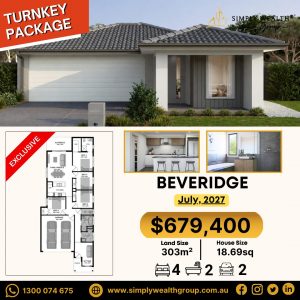
Beveridge House and Land Package — Turnkey Living, Ready July 2027 Looking for a home that gives your family room to grow — without the stress of managing a build? The Beveridge house and land package is Simply Wealth Group’s latest turnkey release, designed for families and investors who want a fixed price and a fixed completion date, with no surprises along the way. Set on a generous 303m² block with an 18.69sq home footprint, this design is built around everyday living. A private courtyard and alfresco extend your space outdoors, while separate family and meals zones give everyone room to spread out — whether that’s a quiet night in or hosting the whole family for dinner. It’s the kind of layout that works just as hard for a growing household as it does for tenants looking for space and comfort. What’s included: 4 bedrooms 2 bathrooms 2 car garage Sleek, modern kitchen Stylish bathroom finishes Functional layout with alfresco living Priced at $679,400, this Beveridge turnkey package is locked in for July 2027 completion — meaning no surprise costs, no shifting timelines, and no guesswork between exchange and handover. Why Beveridge? Beveridge is one of the standout performers in Melbourne’s northern growth corridor, offering the kind of land value and infrastructure growth that both first home buyers and investors are chasing right now. As the suburb continues to develop — with new schools, retail precincts, and transport links progressively rolling out — buying in early has historically been where the strongest capital growth sits. A 4-bedroom, 2-bathroom home in this configuration is consistently in demand across the rental market too, whether you’re planning to live in it long-term or add it to a growing investment portfolio. Why go turnkey? With a turnkey package, the price you’re quoted is the price you pay. Driveway, fencing, landscaping — it’s all locked in before you sign, so there’s no juggling separate contracts with a builder, landscaper, and fencing contractor, and no unexpected costs creeping in along the way. You get keys in hand, ready to move in or lease out from day one — which also means investors can start generating rental income sooner, without the delays that come with managing a build separately. This kind of certainty matters most in a market where construction costs and timelines can shift. Locking in your price now, for a July 2027 completion, protects you from that volatility while still giving you time to plan your finances, finalise your loan, or line up a tenant ahead of settlement. Secure your spot Allocations for this Beveridge house and land package are limited, and July 2027 completion slots are filling fast. Whether you’re a first home buyer ready to plant roots or an investor building your next asset, this is a package worth acting on before the next price release. 📲 WhatsApp us: Message us here 📞 Call: 1300 074 675 🌐 Visit: www.simplywealthgroup.com.au
Read More »
Beverdige Turnkey Package

Turnkey Homes Beveridge | 3 Bed Ready to Build | $608,130

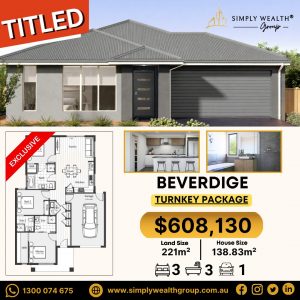
TITLED! BEVERIDGE TURNKEY PACKAGE Turnkey Homes Beveridge:  Turnkey homes Beveridge are transforming how buyers approach property investment. If you’re searching for a home where everything is already planned, titled, and ready to go — you’ve found it. This stunning turnkey homes Beveridge package eliminates uncertainty and puts you on the fast track to building your dream home. Why Choose Turnkey Homes Beveridge? Turnkey homes Beveridge stand out because they combine titled land with pre-designed architecture — eliminating months of planning and delays. The land is titled and ready to build — no more waiting on the title! This is a game-changer for buyers tired of bureaucratic delays. With the title already secured, these turnkey homes Beveridge move forward immediately, perfect for those wanting certainty and a faster path to construction. What Makes These Turnkey Homes Beveridge Special? Turnkey homes Beveridge aren’t just any properties — they’re thoughtfully designed with modern living in mind. Each turnkey homes Beveridge package features a stylish, well-designed layout that maximizes functionality and comfort. With smart use of space throughout, these homes deliver both style and practicality. 3 Bedroom Homes Beveridge Design Features: 3 Bedrooms – Perfect for growing families and modern lifestyles 3 Bathrooms – Convenience for busy households 1 Car Garage – Secure parking and additional storage Land Size: 221m² – Generous block with room for outdoor living House Size: 138.83m² – Efficient, thoughtfully designed interior The Turnkey Advantage Over Traditional Home Buying When you choose turnkey homes Beveridge, you’re choosing speed and certainty. Traditional home building requires: Months searching for land Weeks finding an architect Uncertainty about final design costs Extended timeline to construction Turnkey homes Beveridge eliminate all of this. Everything is pre-planned and ready. Your architect has already done the work. Your design is finalized. Your costs are locked in. All you do is secure financing and begin construction — it’s that straightforward. Investment Potential of Beveridge Beveridge is one of Melbourne’s fastest-growing suburbs. Families and investors alike are choosing 3 bedroom homes Beveridge because of: Strong population growth Excellent schools and community facilities Shopping centers and local amenities Easy access to major transport links Long-term capital growth potential Turnkey homes Beveridge position you in a suburb with genuine future upside. Investment Value At $608,130, this turnkey homes Beveridge package represents exceptional value. You’re acquiring: Titled, ready-to-build land (221m²) Fully designed architectural plans Modern 3-bedroom, 3-bathroom design 138.83m² of premium living space Immediate pathway to construction No hidden costs. No design fees. No architect delays. Just one transparent price for everything. Who Should Consider Turnkey Homes Beveridge? Turnkey homes Beveridge are ideal for: First-time buyers wanting certainty and speed Young families needing modern, functional design Investors seeking ready-to-build opportunities Busy professionals who don’t have time for extended planning Anyone tired of traditional home-building delays The Turnkey Homes Beveridge Opportunity Turnkey homes Beveridge won’t stay on the market long. Serious buyers recognizing the value of titled land + ready design + competitive pricing act quickly. If you’ve been considering a move to Beveridge, or looking for a faster path to building, now is the time. Contact Simply Wealth Group Today Don’t miss out on this turnkey homes Beveridge opportunity. 📱 WhatsApp: https://wa.me/61468175628 📞 Phone: 1300 074 675 🌐 Website: www.simplywealthgroup.com.au
Read More »
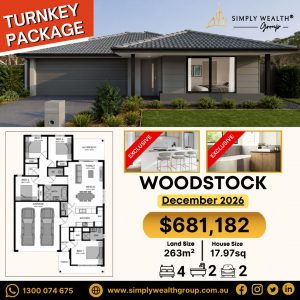
Woodstock Turnkey Package | 4-Bed Home from $681,182

Woodstock Turnkey Package | 4-Bed Home from $681,182

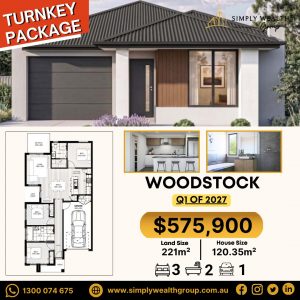
🏠 Get to own a House and Land Package in Wyndham Vale for only $761,929 🏠🏠 Get to own a House and Land Package in Donnybrook for only $635,968! 🏠  EXCLUSIVE HOLD — WOODSTOCK TURNKEY PACKAGE  Ready December 2026! An exclusive opportunity, secured for a limited time.A well-designed family home with an alfresco, spacious living zones, and a functional layout throughout. 4 Bedrooms 2 Bathrooms 2 Car Garage Land Size: 263m² House Size: 17.97sq $681,182This Woodstock turnkey package is currently on exclusive hold — a rare chance to lock in a quality asset before it’s released more broadly. Perfect for families and investors alike. Locked in for December 2026 completion — enquire now to secure your hold. WhatsApp us here: https://wa.me/61468175628  1300 074 675 www.simplywealthgroup.com.au
Read More »
Australia's Housing Approvals

Why Australia’s Housing Approvals Can’t Keep Up With Population Growth

Why Australia’s Housing Approvals Can’t Keep Up With Population Growth Around 17,700 new houses were approved in Australia in July 2026 alone. Meanwhile, the country had over 400,000 more people in the year leading up to then. Approvals and population growth will never match, but the failure to admit this is why first-time buyers and investors are surprised. Planning, workforce, and cost of construction all occur at a government pace.  Migration happens much faster, and this misalignment is something Australians who are seeking house and land packages in Australia are seeing in the form of long waiting periods and increased prices now; to be clear, approvals have always failed to scale. What Is the Housing Shortfall With Respect to Population Growth? In 2025, the population of Australia rose to 27.8 million, having grown by 412,500 persons or by 1.5%. The number of individuals added via Net Overseas Migration was 301,000, representing some 73% of population growth according to the data from the ABS. This number, although less than that registered during the migration boom of 2023, is still a very significant number of households seeking accommodation. However, supply has not risen to meet the challenge, and according to the ABS Building Approvals data for July 2026, the total number of dwelling approvals decreased by 3.6% to 17,687, while private house approvals were down 4.2%. It is important to point out that despite the increase in the number of approvals for construction witnessed in the financial year 2025-26, where 48,778 units of apartments were approved, there is no corresponding increase in the number of construction completions, as shown in the 2026 Report of the NHSC. Get Expert Help Choosing Your Next Property Let’s Talk Now! Why Are Approvals Taking So Long? They cite bureaucracy and then stop, but that is lazy thinking. The problem is multiple problems occurring together: Delays within the planning system: the council assessment process hasn’t caught up to the demands being placed on it. Increases in construction costs: the average approved dwelling price rose to $517,430 in FY25-26, up 5% from the previous year, impacting builder profits. Labor shortages: not enough tradies to get those approvals turned into builds on time. Land supply issues: zoning and infrastructure have fallen behind growth corridors by a lot. Builder collapses: approved projects are either delayed or failing before completion. Address one issue, and the others will continue to hold supply back. This is what most analysis fails to consider. Interested in location advice based on where supply is really restricted, and not simply hyped up? Request a free property assessment from Simply Wealth Group. How Will the Supply Shortage Affect Homebuyers and Renters? With the rise in the number of people being outnumbered by the availability of properties, there will be only one thing: competition. Competition among renters, where vacancy rates will drop and rental prices will grow. Competition for homebuyers, where there will be a reduced number of newly constructed homes, forcing them to spend more money. For the investors, the same problem, which makes life hard for homebuyers, becomes the backbone of rental demand and capital appreciation. The fact alone is not a reason to invest. Rather, it should be a reason to be careful with whom you entrust your purchases. A reliable property investment company in Australia should show you all the statistics of approval-to-completion before suggesting anything. What Should Investors Do About It? Undersupply isn’t a hype cycle; it is a trend, and trends favor the patient, not the panicked. Trying to catch the next “hot suburb” when there’s been a spike in approvals in one month is what makes people overpay. This is what really holds its own over a decade: Invest in locations where infrastructure investment money is locked in, not in promises. Favor a steady income stream over potential growth. Look at approval spikes as a reason to research, not a reason to do anything. Develop a hold strategy that takes into account the fact that undersupply takes years, not months. Arrange for professional property management in Australia right away so that vacancy and upkeep don’t undermine the fundamentals that you’re investing in. It is the difference between a compound portfolio and an unsellable nightmare in five years. Need Help Finding the Right Residential property? Get Your Free Consultation Strategic Positioning in a Market That Isn’t Closing the Gap Any Time Soon Approvals won’t be closing the gap any time soon, but approvals aren’t the only factor; building costs and labor supply are important considerations as well, and both take a lot longer to turn around than making an announcement. You’re going to wait through quite a few more property cycles while you’re waiting for approvals to “catch up.” Simply Wealth Group has helped many ordinary Australians develop their property portfolios on the basis of structural imbalances like this very one over many years; no hype cycles, no FOMO. If you want your property portfolio strategy based on actual supply facts rather than the hype from your listing agent, that’s the discussion to have. Ready to create your property portfolio on the basis of the facts? Speak with us today for a complimentary property valuation. FAQs: Is reduced migration sufficient to address the problem of underapproval? No, not by itself, as net overseas migration has fallen from 530,620 in 2023 to 301,000 in 2025, but the levels of approval remain far lower than required to make up for the under-construction of past years. Currently, construction costs and labor shortages have become the main obstacle, not migration flows. Why does the level of approval of apartments fluctuate so drastically in comparison with houses? It is due to the fact that the construction of apartments requires a small number of large-scale projects to be approved; thus, a single approval changes the monthly rate significantly. In the case of houses, there are many different and small buildings being constructed, which leads to a stable monthly rate. Does an increase in approvals necessarily result in home

Read More »
Investing Under $750K: What's Actually Available in Today's Market1

Investing Under $750K: What’s Actually Available in Today’s Market

Investing Under $750K: What’s Actually Available in Today’s Market Everyone believes that this budget cannot afford anything worthwhile nowadays. It doesn’t mean anything like this; it just means that things have changed since five years ago. This budget allows you to afford something that is completely different from what was available five years ago.  Now, this budget gives you the possibility of buying matured properties in outer growth corridors, an almost new package of land and house, and also good units in the middle ring, located with professional property management in Melbourne after settlement. There will be no chance of getting inner-Melbourne properties, and that is what leads people to overspend. Why Has This Budget Become the New Entry Point for Investors? In five years, $750,000 will be comfortably within the middle ring suburbs of Melbourne. Today, it sits right at the point where outer growth meets affordable middle ring suburbs. Based on Core Logic’s projections midway through 2026, the median price of houses in Melbourne will range anywhere from $850,000 to $920,000. In addition to all of this, the policies of Victoria itself support this figure. With a stamp duty rebate up to the level of $750,000 and a First Home Owner Grant of $10,000 on new properties below this price level, the government of Victoria has effectively established this limit, and the market works on the basis of this price level. Get Expert Help Choosing Your Next Property Let’s Talk Now! What Does the Market Have To Offer for This Amount of Money in Melbourne? Forget the CBD and inner east; discussions begin at a minimum of $1.5 million. In this price range, these are some of your options: A solid three-bedroom or four-bedroom house in outer areas like Melton, Wyndham Vale, and Werribee, where median prices are still in the range of $500,000 to $700,000. A new house-and-land package in growth areas like Rockbank, Kalkallo, or Clyde North, typically with building incentives thrown into the package. A townhouse or unit in middle-ring suburbs like Reservoir, Preston, or Sunshine, where land value does all the heavy lifting. Dual occupancy or granny flat site in selected outer suburbs, great for investors who require two rental yields from one site. Property investors in Melbourne who stick to the above list have historically performed better than those who try and reach for a suburb that they currently cannot afford. Is a House-and-Land Package Better than an Established Home at this Price? There is no right answer because they address different concerns. A house-and-land package gives you a depreciation benefit, reduced cost of maintenance for the first decade, and certainty of the cost of construction. A middle-ring suburb with established housing means that you own the land now, have the rental history on which to base your expected return, and eliminate construction risks. Your losses are the depreciation deductions and sometimes higher maintenance costs for the first few years. Things You Should Verify Before Committing Yourself to This Budget There’s no room for any unforeseen error when numbers are this tight. Before you put down your signature: The suburb’s five-year rental yield trend, rather than just the current one-quarter. Whether the advertised price covers outdoor work, fencing, and driveways, or if they come as “extras” after. Council development plans, because new development may increase or decrease your value based purely on the timing. Your holding cost estimates, which include land tax, insurance, and body corporate fees. If the serviceability buffer on your lender is still good in case the RBA pulls another move, the current cash rate is 4.35%, unchanged from August, with the next review on September 29. Why Is The Quality Of Your Manager More Important Here on This Budget? Here, the margins are smaller, and the quality of ongoing management will impact whether the investment works according to the model. If the management is not up to scratch, the property could end up sitting empty for weeks, being under-rented by an apathetic agent, or picking up maintenance problems over the years to come, which gradually eat away at any gain you made. It’s here where discipline takes priority over enthusiasm. It’s all well and good having a tight budget, but that means little if it’s not managed with the same diligence, proper rent reviews, proactive maintenance, and a manager who takes care of the property like they would an investment of their own rather than an account number. How Does This Kind of Purchase Become a Real Portfolio? A single property in this price range will not make you rich, but no one in his right mind thinks so. The only thing this property can do is provide you with the equity position you will need to be able to purchase again after three or five years, depending on how well you selected your property and how well you have been able to manage it during those years. The wrong approach is trying to think of each of the purchases as a stand-alone deal rather than building up a real property management portfolio that complements each other in their characteristics. Need Help Finding the Right Residential property? Get Your Free Consultation Small Budgets Still Produce Portfolio-Quality Assets This sort of budget would never have bought you an asset in Toorak, nor did it ever intend to. What this budget will do, if you are serious about making it work in your best interest, is provide you with a legitimate opportunity to enter a market which will still favour patient, well-informed investors over those who make ill-considered decisions.  The professionals at Simply Wealth Group have been helping ordinary Australians identify quality assets within precisely this type of budget range, through comprehensive market research instead of speculation. We will help take care of the entire process of acquiring and managing your portfolio, so you can start with everything being done right from the get-go, instead of risking it all to luck.  FAQs: Why can growth corridors provide higher rental returns than

Read More »
Property Investment in Australia

How Migrants Are Building Wealth Through Property Investment in Australia

How Migrants Are Building Wealth Through Property Investment in Australia Starting a new life in Australia often comes with long-term financial goals, and for many migrants, owning property is one of them. Property investment in Australia can become a way to build wealth over time, provided the investment is based on a clear plan rather than a rushed purchase. This is especially relevant now, with negative gearing changes reshaping how residential property investors approach established properties versus new builds. From 1 July 2027, the rules will generally favour eligible new builds for negative gearing, which makes new houses and house and land packages an important option for anyone planning ahead. Why Migrants Are Looking at Property Investment Once migrants settle into Australia, their financial priorities tend to shift. Buying a family home may come first, followed by saving, investing and planning for the future. Property appeals as a physical asset that can generate rental income and grow in value over time, but buying an investment property is a different exercise to buying a home to live in. The decision needs to weigh rental demand, location, finance, and how the property fits into your wider plans. For someone still learning how the Australian market works, having a clear investment strategy makes the process far easier to navigate. Start With Your Own Financial Position Before choosing a property, take a close look at your current finances. Income, savings, existing debts, deposit, and borrowing capacity will all shape what you can realistically invest in, and it’s worth thinking about what your finances might look like in a few years too. A migrant might be planning to buy a family home, grow their family or change employment, and any of these can affect how much they’re comfortable committing to an investment property. Starting with your own financial position helps ensure the property supports your plans rather than pressuring you. Know the Rules Before You Buy Migrants need to understand the rules attached to their specific residency status, since not every migrant is in the same position when buying residential property in Australia. Foreign investment rules can apply to certain buyers, and restrictions differ depending on residency status and property type. Foreign persons are currently banned from purchasing established dwellings in Australia, with limited exceptions such as large-scale redevelopments or build-to-rent projects. As these rules and their timeframes can change, check the current requirements that apply to your circumstances before making a purchase. Tax is another consideration. Obligations can vary depending on residency status, rental income and other circumstances, so speaking with an appropriate tax or financial professional before investing helps avoid surprises later. What the Negative Gearing Changes Mean Negative gearing for residential property will generally be limited to eligible new builds from 1 July 2027. For established residential properties purchased after 7:30 pm AEST on 12 May 2026, rental losses will generally no longer be deductible against other income such as salary and wages. Instead, losses can be deducted against residential property income, including relevant capital gains, with unused losses carried forward. Properties already held before 7:30 pm AEST on 12 May 2026 generally retain their existing negative gearing treatment while they continue to be held. For a migrant considering a first investment, the choice between an established property and a new build deserves real attention. That said, tax treatment alone shouldn’t drive the decision. The property still needs to make sense as an investment in its own right. Why New Houses and House and Land Packages Could Be Worth Considering A house and land package combines the purchase of land with the construction of a new home. With eligible new builds retaining negative gearing access, this can offer migrants an alternative to purchasing an established property as they plan ahead. This is an area where Simply Wealth Group has specialist experience, focusing on house and land opportunities and new homes designed around an investor’s broader strategy. Beyond the tax treatment, location, expected rental demand, surrounding infrastructure, property design and future development of the area all affect how the investment performs. A tax benefit alone doesn’t make a property a good one. Explore Your Property Investment Options If you’re a migrant planning your next step in the Australian property market, getting a clear understanding of your options can help you make a more informed decision. We can help you explore property investment strategies and house and land opportunities based on your individual goals and circumstances. CTA: Speak with Simply Wealth Group about your property investment strategy. Look at the Property, Not Just the Tax Benefit Location is one of the first things to weigh up. Access to employment, transport, schools, shopping and amenities influences how appealing an area is to tenants, and population growth or new infrastructure can affect future demand too. The house itself matters just as much. A practical floor plan, a suitable number of bedrooms, and features tenants actually want all influence rental appeal. Expected rental income should be considered alongside the costs of owning the property, since the complete picture gives a far more realistic view of whether the investment fits your strategy. How Property Investment Advisors Can Help Migrants may understand property well in their home country but still find the Australian market unfamiliar, since lending practices, taxation, and purchasing processes can all work differently here. Simply Wealth Group‘s advisory approach focuses on understanding an investor’s objectives and building a property wealth strategy around their circumstances, with advisers who have experience as property investors themselves. For a migrant, this kind of guidance helps bring the different pieces together, so finance, property selection, rental returns and future portfolio plans are considered as a whole rather than in isolation. Keep Reviewing Your Strategy Buying an investment property is only one part of the process. Rental income, expenses, interest rates, property values and personal circumstances all change over time, so a strategy that made sense a few years ago may need revisiting. This matters even more once you’re building a

Read More »
Tax Benefits of Property Investment: What Australian Investors Need to Know?

Tax Benefits of Property Investment: What Australian Investors Need to Know?

Tax Benefits of Property Investment: What Australian Investors Need to Know? Property investment in Melbourne is not just about finding a good address. It is about understanding, from day one, how tax rules work in your favour and how to structure your purchase so you keep more of what you earn. At Simply Wealth Group, we help clients see the full picture before they buy, not after, so every decision supports the bigger goal: financial freedom and peace of mind. Tax benefits are a real part of what makes property investment work. But they are not the whole story. Property investment in Melbourne should also be approached with a long-term strategy that considers growth potential, financing, and your personal financial goals. The right property, the right structure, and the right ongoing support matter just as much as any deduction. That is why we look at your investment from every angle, not just the numbers on paper. Why Tax Planning Comes First Many investors think about finance and location, then leave tax as an afterthought. We do it differently. Understanding what you can claim, keeping accurate records, and knowing your obligations should be part of your plan from the very beginning, not something you figure out at tax time. Investment properties generate rental income, and a portion of your ongoing costs may be deductible against that income under current Australian Taxation Office rules. Every investor’s situation is different, which is why we sit down with you individually rather than offering one-size-fits-all advice. What You Can Claim Owning an investment property comes with real, ongoing costs. Many of these can work in your favour at tax time. Interest on your investment loan, usually the largest deductible expense Property management fees, council rates, insurance, and maintenance Accounting fees and advertising costs for finding tenants There is one distinction that catches out a lot of new investors: the difference between a repair and an improvement. A repair restores something to its original condition. An improvement adds value or extends the property’s life, and the two are treated differently under tax law. This is exactly why we recommend keeping every invoice and receipt from day one. It makes your annual return simpler and gives you a clear picture of how your property is actually performing. Depreciation: A Deduction Investors Often Miss Depreciation lets you claim the decline in value of eligible building elements and fixtures over time. You are not paying this out of pocket, yet it can still reduce what you owe. A depreciation schedule from a qualified quantity surveyor identifies exactly what you can claim. At Simply Wealth Group, we arrange this for our clients so nothing is left on the table. It is one of the simplest ways to strengthen your return year after year, and it is often overlooked by investors managing things on their own. For anyone building a genuine property investment portfolio, depreciation should be considered alongside cash flow and capital growth, not treated as a separate afterthought. Want a clearer picture of what your property could return? Contact Simply Wealth Group for a free consultation. Negative Gearing: A Tool, Not a Strategy Negative gearing comes up often in property investment in Melbourne conversations, and it is worth understanding properly. It simply means your property expenses are higher than your rental income for the year. Under current tax law, that loss may offset other taxable income. It is a useful mechanism, but it should never be the reason you buy a property. The property still needs to work as an asset in its own right: the right location, genuine rental demand, and a clear path to growth. We help clients evaluate properties on those fundamentals first, with tax treatment as part of the overall structure, not the headline reason to buy. What Changes from 2027 Investors need to pay close attention here. Under the federal government’s 2026 budget reforms, negative gearing will be limited to new builds from 1 July 2027, and established properties purchased after budget night will no longer be eligible. If you already own an established investment property, or you are under contract before the cutoff, your current arrangement is protected. But for anyone buying after this point, established homes will not carry the same tax advantage they once did. This is exactly where house and land packages stand out. Since Simply Wealth Group specialises in house and land builds, our clients are already positioned on the right side of this change. A new build purchased today continues to qualify for negative gearing well beyond the 2027 deadline. For investors weighing established versus new stock, this is no longer just a lifestyle preference. It is becoming a real tax planning decision, and getting ahead of it now means avoiding a scramble later. Capital Gains Tax and Planning Your Exit Tax planning does not stop the day you buy. It matters again when you decide to sell. If your property has grown in value, Capital Gains Tax may apply, depending on your circumstances and current legislation. Purchase contracts and settlement statements Records of improvement costs and selling expenses Keeping these organized from the start saves time and stress later, and gives your accountant everything they need to get your return right the first time. Tax laws also change, which is why we review our clients’ strategies regularly rather than setting a plan once and leaving it. Building a Property Investment Portfolio That Works Buying more properties is not the same as building a stronger portfolio. A successful portfolio takes planning: each property needs to earn its place based on affordability, rental demand, ongoing costs, and how it fits your long-term goals. This is where working with experienced property investment advisors makes a real difference. At Simply Wealth Group, we work alongside your accountant and lender, so your tax position, your finance, and your long-term strategy are all working together, not in isolation. Every client is different, and we take the time to build a plan around

Read More »
eofy 2026 for property

2026 Property Investor Guide: The Ultimate Income and Deduction Playbook

2026 Property Investor Guide: The Ultimate Income and Deduction Playbook Introduction In 2026, the ATO is no longer relying on what you report. It is actively checking it. With expanded data matching across rental bond authorities, property managers, and short term platforms like Airbnb and Stayz, property investors are under closer scrutiny than ever. Many investors are not audited because they intentionally do the wrong thing, but because they misunderstand what needs to be declared and what can actually be claimed. The rules have also become more complex. Draft guidance such as TR 2025/D1 signals how the ATO is tightening its position on private use, holiday homes, and lifestyle properties. At the same time, common mistakes around loan interest, repairs, and depreciation continue to trigger adjustments and penalties. This guide breaks down the key areas of your rental property tax return based on the ATO’s Rental Property Statement. It will help you understand what must be declared as income, what you can legitimately claim as deductions, and where investors most commonly get it wrong. I. What You Must Declare (Assessable Income) One of the most common mistakes investors make is declaring only the net rent they receive. The ATO requires you to declare gross income before any fees or deductions. Gross RentYou must include every dollar paid by a tenant or guest. This includes weekly rent, short term accommodation income, and any cleaning or service fees charged through platforms like Airbnb or Stayz.Example: If your agent deducts $3,000 in fees and sends you $27,000, you must still declare $30,000. Bond Money RetainedIf you keep part or all of a tenant’s bond to cover unpaid rent or damage, that amount is treated as income. Insurance PayoutsIf you receive insurance for loss of rent, it must be declared as income. Payments for property damage are treated differently and may fall under capital gains rules. ReimbursementsIf a tenant reimburses you for a cost you have already claimed as a deduction, such as a repair or water bill, that reimbursement must be declared as income. Discounted Rent to Family or FriendsYou must still declare the income received. If the rent is below market value, your deductions may be limited to the amount of income earned. II. Expense Details: Maximising Your Deductions The Green Zone (Immediate Deductions) These are expenses you can generally claim in full in the same financial year. Advertising and CommissionsYou can claim agent fees, platform commissions, and listing costs.You cannot claim the value of your own time managing the property. RepairsRepairs relate to fixing something that is broken or damaged.Examples include repairing a leaking tap, replacing a broken window, or fixing storm damage. What you cannot claim here are initial repairs. If the damage existed when you purchased the property, the cost is considered capital in nature. A simple rule: if the work improves or replaces the whole asset rather than fixing damage, it is likely capital. Operational CostsCleaning, gardening, and pest control costs are deductible when incurred during rental periods. The Amber Zone (Holding Costs and Apportionment) These expenses are often deductible, but may need to be apportioned. Interest on LoansYou can claim interest on the portion of the loan used for the investment property.You cannot claim interest on funds used for personal purposes such as holidays, cars, or private expenses. Example: If you redraw from your mortgage for personal use, you must separate and exclude that portion of interest. Rates and TaxesCouncil rates, water rates, and land tax are generally deductible.You cannot claim water usage charges that are paid directly by the tenant. InsuranceLandlord, building, and contents insurance are deductible.Personal insurance such as life, trauma, or income protection is not. Apportionment RulesIf the property is used privately or is not genuinely available for rent, expenses must be apportioned.This includes: Private stays by the owner Periods where the property is not actively listed for rent Renting below market value III. Claiming Over Time Not all expenses can be claimed immediately. Some must be claimed over several years. Building Write Off (Capital Works)Most residential properties allow a deduction of 2.5 percent per year over 40 years.Eligible build to rent developments may qualify for an accelerated 4 percent rate. Depreciation (Plant and Equipment)Assets such as appliances, carpets, blinds, air conditioning units, and hot water systems are depreciated over their effective life.This is a key area many investors miss or underclaim. RenovationsMajor upgrades such as new kitchens, bathrooms, or extensions are capital works and must be depreciated over time.They should not be claimed as repairs. Instant Asset Write OffThis may apply only if you are genuinely carrying on a rental property business, which is uncommon and depends on your circumstances.Most individual investors will not qualify and will instead claim depreciation over time. IV. The Absolute No List (Common Audit Triggers) Travel ExpensesTravel costs related to inspecting or maintaining a residential rental property are not deductible. This includes flights, fuel, and accommodation. Borrowing Costs Over $100Expenses such as loan establishment fees and lender’s mortgage insurance must be spread over five years. The Leisure Facility Risk (TR 2025/D1)If you use a holiday home privately during peak periods such as Christmas or Easter, the ATO may classify it as a lifestyle asset. The consequence can be severe. The ATO may deny key deductions such as interest, rates, and land tax for the entire year. Keeping accurate records of private use is essential. Investor Action Checklist for 2026 Declare gross income, not net amounts received Review loan redraws and separate personal use Ensure ownership percentages match your tax return Keep a clear record of any private use Confirm your depreciation schedule is up to date Final Word Property investment offers strong tax advantages, but only when structured and reported correctly. Most costly mistakes are not aggressive claims, but simple misunderstandings that compound over time. Getting it right can mean the difference between maximising your return and triggering an ATO review. Need Help Getting This Right? If you are not completely confident your property is structured correctly

Read More »
Melbourne Buyers Window

Unlocking the Window: Why the April 2026 Cotality Report is a Game-Changer for Melbourne Buyers

Melbourne Housing: Why the “Buyer’s Friend” is 2026’s Best Kept Secret If you’ve been on the fence about the Melbourne property market, the latest Cotality Monthly Housing Chart Pack (April 2026) has a clear message: the window of opportunity you’ve been waiting for is officially open. While other capital cities are hitting record-breaking highs, Melbourne is moving to a different beat—one that favors the prepared buyer. Here is why the latest data suggests that “waiting for a better time” might actually be your biggest risk. 1. The “Buyer’s Friend” Advantage While the national market grew by 2.1% last quarter, Melbourne was the only major capital to see a meaningful cooling, with values dipping -0.6%. In a country where Perth and Brisbane are soaring at double-digit annual growth, Melbourne’s relative “cool” is a rare gift for buyers. Below the Peak: Melbourne values are currently -1.3% below the record high seen in March 2022. Negotiating Room: With quarterly values softening, the frantic “fear of missing out” has been replaced by a market where buyers have more leverage at the negotiating table. 2. The “Move-Up” Window is Open The Cotality report highlights a significant “stratified” trend in Melbourne. The “cooling” isn’t happening equally across the board, which creates a unique strategy for those looking to upgrade: The Premium Dip: The most expensive 25% of Melbourne homes saw the sharpest decline, dropping -1.6% in value this quarter. Middle-Market Stability: The middle 50% of the market remained completely flat at 0.0%. The Strategy: If you own a mid-tier home and want to upgrade to a premium property, the “price gap” between the two has narrowed. Your current home is holding its value while your “dream” home just got a little more accessible. 3. The Hidden Cost of Staying on the Fence Many people stay on the fence to “save more,” but the Cotality data shows that the rental market is making that a losing game. Rents are Accelerating: Melbourne rents rose 4.4% over the past year. No Place to Hide: The vacancy rate is a razor-thin 1.6%, meaning competition for rentals is often as fierce as the buying market. The Math: With rental yields sitting at 3.7%, every month you wait is a month you are paying down a landlord’s equity rather than your own. 4. Why Melbourne is Different: The Supply Factor The “Chart of the Month” in the Cotality report explains why Melbourne hasn’t exploded like Perth or Brisbane. Historically, Victoria has built more housing relative to its population growth than any other state, accounting for roughly one-third of all national completions. This healthy supply-demand balance is exactly what makes Melbourne a “Buyer’s Friend”—you have more choices and less of the frantic supply-starved competition seen elsewhere. The Verdict: Strategic Timing Yes, the RBA lifted the cash rate to 4.1% in March. Yes, borrowing capacity is tighter. But the April 2026 Cotality report makes one thing clear: Melbourne is the only major market offering buyers a genuine “breather”. History shows these cooling phases don’t last forever. Once the trend turns positive again, the window of opportunity becomes much smaller—and often more expensive. What This Means for You The opportunity is there—but the real question is: what does this actually look like for you? Everyone’s situation is different. Your income, savings, borrowing power, and goals all play a part in what you can realistically do right now. And this is where most people get stuck. They understand the market is shifting, but they’re not quite sure what their next step should be. Not sure if you can actually buy yet? Let’s find out. Have a quick, no-pressure chat with us and we’ll walk you through: What you could realistically afford What options are available to you right now What your next step could look like So instead of guessing, you’ll have a clear idea of where you stand after speaking with our team. [Check Your Buying Position]

Read More »