Negative Gearing Explained: What High-Income Earners Need to Know
Negative Gearing Explained: What High-Income Earners Need to Know Negative gearing can be a useful part of a property investment strategy for high-income earners, but it should never be the main reason to buy an investment property. For those working with a property investment company in Australia that investors can trust, understanding the numbers behind the strategy is essential. A property is negatively geared when its deductible expenses are higher than the rental income it produces, creating a rental loss that may reduce taxable income under the current rules. The important point is that the investor still carries the shortfall. With changes to Australia’s negative gearing rules due to take effect from 1 July 2027, Australian investors need to understand how the strategy works and, more importantly, whether it makes sense within their broader wealth plan. What Is Negative Gearing? The basic concept is straightforward. If an investment property generates $40,000 in rental income but has $50,000 in eligible deductible expenses, it has produced a $10,000 rental loss. Need Help Finding the Right Residential Property? Get Your Free Consultation Under the current arrangements, an eligible investor may be able to offset that loss against other taxable income. For a high-income earner, this can reduce taxable income and potentially reduce the amount of tax payable. However, a $10,000 property loss does not mean you receive $10,000 back from the Australian Taxation Office. You have still spent more on the property than you received in rent. The tax deduction may reduce the after-tax cost of holding the property, but it does not eliminate the cost. That distinction is important because negative gearing should be considered as part of an investment strategy, rather than as a tax-saving exercise. Why Does Negative Gearing Appeal to High-Income Earners? The attraction largely comes down to taxable income. Someone earning a substantial salary may have more taxable income against which an eligible rental loss can potentially be offset under the current rules. This can make the after-tax cash-flow position of a negatively geared property more manageable. But a high income does not make a poor investment a good one. If an investor pays too much for a property or buys in a location with weak rental demand, the tax deduction does not fix the underlying problem. The property still needs to have sound fundamentals and a clear role within the investor’s long-term strategy. This is consistent with Simply Wealth Group approach to property investment. The focus is on developing a strategy around the investor’s objectives while considering factors such as location, rental demand, and long-term growth potential. Negative gearing can support that strategy, but it should not create it. A Tax Deduction Is Not Your Investment Return This is one of the most important points for investors to understand. Suppose an investment property produces a $15,000 rental loss. An eligible investor may be able to use that loss to reduce taxable income, but the investor has not made $15,000. The property has cost more to hold than it has generated in rental income. The actual tax benefit will depend on the investor’s circumstances and the rules that apply. This is why the better question is not simply, “How much tax will I save?” Instead, ask whether you can comfortably hold the property if the cash-flow shortfall continues for longer than expected. Rental income can change, interest costs can increase, vacancies can occur, and unexpected repairs can arise. A high income may provide greater capacity to manage these circumstances, but it does not remove the risk. Ready to Make Your Property Investment Strategy Work Harder? Whether you’re considering your first investment or looking at your existing portfolio, the right strategy starts with understanding the numbers, risks and long-term opportunities. [Book a Property Strategy Consultation] The Risks of Negative Gearing Negative gearing creates a cash-flow commitment because the investor must fund the difference between rental income and property expenses. That may be manageable today, but investors should consider what could happen if circumstances change. Interest rates may rise, a property may remain vacant or an unexpected expense may require additional funds. Personal income can also change over time. The risk becomes more significant as an investor builds a larger portfolio. One property with a manageable shortfall is very different from several properties that all require regular financial support. This is why effective property management portfolio planning becomes increasingly important as an investor builds a larger portfolio. Simply Wealth Group’s portfolio management service focuses on reviewing existing properties, identifying underperforming assets and considering strategies to improve the overall portfolio. Building a larger portfolio is not automatically the same as building a stronger one. Each property needs to serve a purpose. What Is Changing From 1 July 2027? High-income investors also need to understand the changes coming to negative gearing. From 1 July 2027, negative gearing for residential property will generally be limited to eligible new builds. Properties acquired before 7:30 pm AEST on 12 May 2026 are protected by grandfathering arrangements. For established residential properties acquired after that cutoff, rental losses will generally no longer be deductible against non-residential income such as salary and wages. Instead, eligible losses can be used against residential property income, including relevant capital gains, with unused losses carried forward. Eligible new builds will retain access to negative gearing against other taxable income. For investors considering their next purchase, this means the tax treatment of an established property and a new build may be different from 1 July 2027. However, the policy change does not alter the basic investment principle. A property should not be purchased simply because its tax treatment appears attractive. What Should High-Income Investors Consider Before Buying? Start with the property, not the tax deduction. Consider whether the location has genuine rental demand and whether the purchase price is reasonable. Understand the expected rental income and all the costs involved in holding the property. You should also consider how the property fits with your existing assets and whether you can comfortably manage
How Property Investment Can Legally Reduce Your Tax Bill
How Property Investment Can Legally Reduce Your Tax Bill Property investment can legally reduce your tax bill when eligible expenses, depreciation and other deductions are claimed correctly under Australian tax rules. But a tax deduction is not a reason to buy a property that does not make financial sense. For investors considering a property investment company in Australia, the disciplined approach is to assess the property, finance, rental income, cash flow and portfolio role first, then understand the tax treatment. For Australian investors, this keeps tax planning connected to the broader investment strategy rather than making it the sole reason for a purchase. Why Tax Planning Should Start Before You Buy Tax should not be something you consider only after settlement. The structure of an investment and use of borrowed funds can affect what may be claimed. The Australian Taxation Office states that rental income must be declared and that many, but not all, rental property expenses may be deductible. Some expenses can be claimed in the income year incurred, while others must be claimed over several years. Expenses may also need to be apportioned when a property is privately used, or a loan has investment and personal purposes. A tax-focused approach gives investors a framework for discussing property selection, finance, ownership and tax treatment before committing capital. What Property Expenses May Be Deductible? Investment properties involve ongoing costs, and some may qualify for deductions when they meet the requirements. Examples include eligible loan interest, property management fees, insurance, council rates, advertising and certain maintenance or professional expenses. Do not treat every expense as automatically deductible. Repairs and improvements can receive different tax treatment. A repair generally restores an item, while an improvement may add value or extend its useful life. Good records make this easier. Keep: loan statements showing how borrowed funds were used; invoices and receipts for repairs, maintenance, and improvements; and property management statements and insurance records. Depreciation Can Support the Tax Position Eligible building costs and depreciating assets may provide deductions over time, subject to the applicable rules. Depreciation can reflect a decline in value without the same cash outflow during the year. Get Expert Help Choosing Your Next Property Let’s Talk Now! A qualified quantity surveyor can prepare a depreciation schedule identifying relevant amounts for your tax professional. For investors comparing a property investment company, weigh depreciation alongside price, rental demand, financing and portfolio role. Negative Gearing: Understand the Trade-Off Negative gearing is often discussed as though it is a benefit without a cost. That is too simple. A rental property is generally negatively geared when deductible expenses are greater than rental income. Under applicable rules, the resulting rental loss may be deductible against rental and other income. If other income is not enough to absorb the loss, the ATO states that the loss may be carried forward. The tax outcome can reduce taxable income, but the investor still has an underlying cash shortfall. Negative gearing should be treated as one part of an investment structure, not the investment strategy itself. The property still needs sound fundamentals: price, rental demand, financing, costs, location, and suitability for the investor’s goals. What the 2027 Changes Mean for Investors Federal reforms make tax planning more relevant. From July 1, 2027, negative gearing for residential property will generally be limited to eligible new builds. Established residential properties purchased after 7:30 pm AEST on May 12, 2026 will generally have rental losses treated differently, with deductions against non-residential income restricted under the new framework. For Australian investors, the established-versus-new-build decision deserves attention. It does not mean a new build is automatically the right choice. Price, location, construction, rental demand, financing and strategy still matter. The above reflects the rules as at the time of writing and is correct as at publication date; confirm current settings with a tax professional before purchasing. Building a Tax-Aware Property Management Portfolio A property management portfolio should be assessed as a connected strategy, not simply a list of properties. Each asset contributes different rental income, expenses, financing requirements, and risks. As a portfolio grows, reviews can help assess whether the strategy still fits. Income, interest rates, rental conditions, expenses, and legislation can affect individual properties. Investment advisors can add value here. Their role should be to connect property selection, finance, portfolio planning, and long-term objectives. Tax advice itself should come from an appropriately qualified tax professional. A disciplined review can include: checking rental income against ownership costs; reviewing debt and finance structure; and considering whether a new property strengthens the portfolio rather than simply increasing its size. We takes an integrated approach across property investment, mortgage solutions, portfolio management and related support. Its services are built around education, guidance and ongoing investment support. [Get Portfolio Guidance From Simply Wealth Group] Tax Benefits Should Support the Investment, Not Drive It The biggest mistake is treating a tax saving as proof that an investment is good. It is not. If an investor spends money to create a deduction, the deduction does not erase the expense. The better question is whether the property makes sense before tax and whether its role in the portfolio remains appropriate after tax. For anyone researching a property investment company in Australia, ask how the strategy is developed, how properties are assessed, how finance is structured and what support continues after settlement. Good advice should challenge assumptions, explain trade-offs and make the numbers easier to understand. Capital Gains Tax Also Matters If an investment property is later sold, Capital Gains Tax may apply on the difference between the sale proceeds and the property’s cost base, which includes the purchase price plus eligible acquisition and improvement costs. Investors who have held the property for more than twelve months may be eligible for a CGT discount, subject to individual circumstances and the rules in effect at the time of sale. Timing the sale matters too. A property purchased before or after the May 2026 negative gearing cutoff may carry a different tax profile at
Tax Benefits of Property Investment: What Australian Investors Need to Know?
Tax Benefits of Property Investment: What Australian Investors Need to Know? Property investment in Melbourne is not just about finding a good address. It is about understanding, from day one, how tax rules work in your favour and how to structure your purchase so you keep more of what you earn. At Simply Wealth Group, we help clients see the full picture before they buy, not after, so every decision supports the bigger goal: financial freedom and peace of mind. Tax benefits are a real part of what makes property investment work. But they are not the whole story. Property investment in Melbourne should also be approached with a long-term strategy that considers growth potential, financing, and your personal financial goals. The right property, the right structure, and the right ongoing support matter just as much as any deduction. That is why we look at your investment from every angle, not just the numbers on paper. Why Tax Planning Comes First Many investors think about finance and location, then leave tax as an afterthought. We do it differently. Understanding what you can claim, keeping accurate records, and knowing your obligations should be part of your plan from the very beginning, not something you figure out at tax time. Investment properties generate rental income, and a portion of your ongoing costs may be deductible against that income under current Australian Taxation Office rules. Every investor’s situation is different, which is why we sit down with you individually rather than offering one-size-fits-all advice. What You Can Claim Owning an investment property comes with real, ongoing costs. Many of these can work in your favour at tax time. Interest on your investment loan, usually the largest deductible expense Property management fees, council rates, insurance, and maintenance Accounting fees and advertising costs for finding tenants There is one distinction that catches out a lot of new investors: the difference between a repair and an improvement. A repair restores something to its original condition. An improvement adds value or extends the property’s life, and the two are treated differently under tax law. This is exactly why we recommend keeping every invoice and receipt from day one. It makes your annual return simpler and gives you a clear picture of how your property is actually performing. Depreciation: A Deduction Investors Often Miss Depreciation lets you claim the decline in value of eligible building elements and fixtures over time. You are not paying this out of pocket, yet it can still reduce what you owe. A depreciation schedule from a qualified quantity surveyor identifies exactly what you can claim. At Simply Wealth Group, we arrange this for our clients so nothing is left on the table. It is one of the simplest ways to strengthen your return year after year, and it is often overlooked by investors managing things on their own. For anyone building a genuine property investment portfolio, depreciation should be considered alongside cash flow and capital growth, not treated as a separate afterthought. Want a clearer picture of what your property could return? Contact Simply Wealth Group for a free consultation. Negative Gearing: A Tool, Not a Strategy Negative gearing comes up often in property investment in Melbourne conversations, and it is worth understanding properly. It simply means your property expenses are higher than your rental income for the year. Under current tax law, that loss may offset other taxable income. It is a useful mechanism, but it should never be the reason you buy a property. The property still needs to work as an asset in its own right: the right location, genuine rental demand, and a clear path to growth. We help clients evaluate properties on those fundamentals first, with tax treatment as part of the overall structure, not the headline reason to buy. What Changes from 2027 Investors need to pay close attention here. Under the federal government’s 2026 budget reforms, negative gearing will be limited to new builds from 1 July 2027, and established properties purchased after budget night will no longer be eligible. If you already own an established investment property, or you are under contract before the cutoff, your current arrangement is protected. But for anyone buying after this point, established homes will not carry the same tax advantage they once did. This is exactly where house and land packages stand out. Since Simply Wealth Group specialises in house and land builds, our clients are already positioned on the right side of this change. A new build purchased today continues to qualify for negative gearing well beyond the 2027 deadline. For investors weighing established versus new stock, this is no longer just a lifestyle preference. It is becoming a real tax planning decision, and getting ahead of it now means avoiding a scramble later. Capital Gains Tax and Planning Your Exit Tax planning does not stop the day you buy. It matters again when you decide to sell. If your property has grown in value, Capital Gains Tax may apply, depending on your circumstances and current legislation. Purchase contracts and settlement statements Records of improvement costs and selling expenses Keeping these organized from the start saves time and stress later, and gives your accountant everything they need to get your return right the first time. Tax laws also change, which is why we review our clients’ strategies regularly rather than setting a plan once and leaving it. Building a Property Investment Portfolio That Works Buying more properties is not the same as building a stronger portfolio. A successful portfolio takes planning: each property needs to earn its place based on affordability, rental demand, ongoing costs, and how it fits your long-term goals. This is where working with experienced property investment advisors makes a real difference. At Simply Wealth Group, we work alongside your accountant and lender, so your tax position, your finance, and your long-term strategy are all working together, not in isolation. Every client is different, and we take the time to build a plan around
House and Land in Beveridge | Full Turnkey Home $693,250
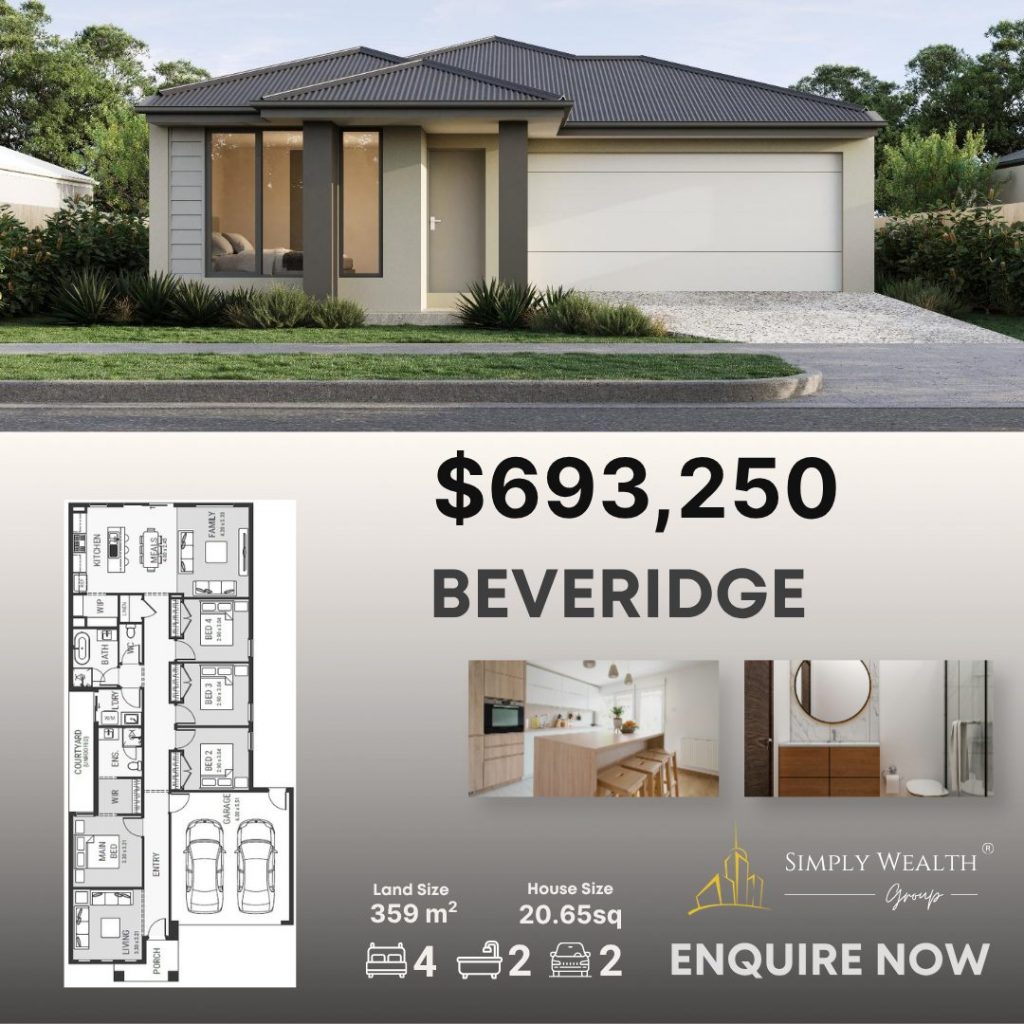
Explore this modern 4-bedroom house and land package in Beveridge. Featuring a full turnkey finish, quality inclusions, family-friendly design, and excellent long-term investment potential, this home is ideal for first home buyers, families, and investors seeking value in Melbourne’s growing northern suburbs.
Advice for Young First Home Buyers
Unsurprisingly, one of the biggest hurdles for young people getting a mortgage is affordability. Melisa Sloan, founder of Madison Sloan Lawyers and author of Big Moments said that high demand and property shortages make things even tougher. “The biggest hurdle is affordability and obtaining finance in an environment where property prices, particularly in city areas are relatively high. Saving for a deposit and the ability to service a mortgage has increasingly become difficult for young people over the past two years, with many now reliant on parental or other family help to obtain a mortgage and get into the property market,” said Sloan. “Many people with good jobs and the ability to service a loan find themselves unable to obtain a mortgage because they do not have a sufficient deposit that is required by lenders. Additionally, property shortages continue to make it difficult for people for young people to get a mortgage.” You may read the whole article here:https://bit.ly/4d1mYQg
New Properties for Sale Up 1.3% – PopTrack
New listings in the housing market have increased year-on-year despite a seasonal slowdown, according to the latest PropTrack Listings Report. Compared to the previous month, June 2024 saw new listing volumes down 15%, marking the transition into a quieter season. Every capital city and regional area reported a monthly decrease in new listings in June. However, new listings were 1.3% higher compared to June 2023. Among capital cities, only Perth (-5.7%), Darwin (-6.7%), and Canberra (-2.6%) saw a year-on-year decline in new listings. In regional markets, only South Australia (+8.2%) experienced an increase in new listings over the year. You may read the whole article here:https://bit.ly/4bIZ8rt
Consumer Spending Up Over the Year
According to NAB’s transaction data, consumer spending has remained steady, with total spending on both goods and services flat. Despite this, discretionary spending saw a modest increase of 0.6% month-on-month, while non-discretionary spending declined by 1%. The decrease in non-discretionary spending was primarily due to a significant drop in expenditure on utilities and fuel. Annual growth in consumer spendingConsumer spending is up 5.6% over the past 12 months. However, consumption growth has softened since the beginning of this year, according to Alan Oster, group chief economist at NAB. You may read the whole article here:https://bit.ly/3zPcrcq
ANZ Predicts Possible RBA Rate Hike in August
Despite speculation that the Reserve Bank of Australia (RBA) might raise the official cash rate at its August meeting, ANZ has forecasted that rates will remain unchanged until February 2025, when it predicts a rate cut. The bank noted that while the Reserve Bank kept the cash rate on hold at 4.35% at its June meeting, the post-meeting statement was slightly more hawkish, with the RBA board stating that they are willing to “do what is necessary” to return inflation to target and will remain vigilant to upside risks in inflation. “Following the stronger than expected monthly inflation print for May, there has been some talk about the possibility of a hike at the RBA’s August meeting,” ANZ said in its report, authored by economists Sophia Angala, Madeline Dunk and Catherine Birch. You may read the whole article here:https://bit.ly/3zD0o29
Consumers Fear Rate Hike Impact
An unexpected drop in confidence saw consumer expectations for variable mortgage rates jump 12.8 per cent in July. According to the Westpac-Melbourne Institute’s Mortgage Rate Expectations Index, this is “the steepest monthly rise since we began running this question in every survey at the start of 2022.” The historical average figure of the index is 143.8. In the last three months, however, there has been a 30 per cent surge, with a below-average read of 122.8 in April to 159.2 in July. What is being dubbed a “sudden hawkish turn” is reportedly the most abrupt change seen in the last seven years. Currently, just under 60 per cent of consumers are expecting a mortgage rate rise over the next year. You may read the whole article here:https://bit.ly/3W0gzhj
Bendigo Bank: RBA Cash Rate to Stay Unchanged All Year
Resolve Finance has announced that the 2024 financial year was a record year for the business, with loan volumes surpassing $1.74 billion. This represents a substantial 11% year-on-year increase for the broker franchise, highlighting its continued growth, and success of the franchise business in the highly competitive mortgage broking industry. It comes after a bumper 2023 for the broker network. A significant portion of this growth can be attributed to strong first-time buyer activity. The number of First Home Buyer schemes and grants Resolve brokers have assisted with has increased by 29% from FY23 to FY24. You may read the whole article here:https://bit.ly/4eT0anx