2026 Property Investor Guide: The Ultimate Income and Deduction Playbook
2026 Property Investor Guide: The Ultimate Income and Deduction Playbook Introduction In 2026, the ATO is no longer relying on what you report. It is actively checking it. With expanded data matching across rental bond authorities, property managers, and short term platforms like Airbnb and Stayz, property investors are under closer scrutiny than ever. Many investors are not audited because they intentionally do the wrong thing, but because they misunderstand what needs to be declared and what can actually be claimed. The rules have also become more complex. Draft guidance such as TR 2025/D1 signals how the ATO is tightening its position on private use, holiday homes, and lifestyle properties. At the same time, common mistakes around loan interest, repairs, and depreciation continue to trigger adjustments and penalties. This guide breaks down the key areas of your rental property tax return based on the ATO’s Rental Property Statement. It will help you understand what must be declared as income, what you can legitimately claim as deductions, and where investors most commonly get it wrong. I. What You Must Declare (Assessable Income) One of the most common mistakes investors make is declaring only the net rent they receive. The ATO requires you to declare gross income before any fees or deductions. Gross RentYou must include every dollar paid by a tenant or guest. This includes weekly rent, short term accommodation income, and any cleaning or service fees charged through platforms like Airbnb or Stayz.Example: If your agent deducts $3,000 in fees and sends you $27,000, you must still declare $30,000. Bond Money RetainedIf you keep part or all of a tenant’s bond to cover unpaid rent or damage, that amount is treated as income. Insurance PayoutsIf you receive insurance for loss of rent, it must be declared as income. Payments for property damage are treated differently and may fall under capital gains rules. ReimbursementsIf a tenant reimburses you for a cost you have already claimed as a deduction, such as a repair or water bill, that reimbursement must be declared as income. Discounted Rent to Family or FriendsYou must still declare the income received. If the rent is below market value, your deductions may be limited to the amount of income earned. II. Expense Details: Maximising Your Deductions The Green Zone (Immediate Deductions) These are expenses you can generally claim in full in the same financial year. Advertising and CommissionsYou can claim agent fees, platform commissions, and listing costs.You cannot claim the value of your own time managing the property. RepairsRepairs relate to fixing something that is broken or damaged.Examples include repairing a leaking tap, replacing a broken window, or fixing storm damage. What you cannot claim here are initial repairs. If the damage existed when you purchased the property, the cost is considered capital in nature. A simple rule: if the work improves or replaces the whole asset rather than fixing damage, it is likely capital. Operational CostsCleaning, gardening, and pest control costs are deductible when incurred during rental periods. The Amber Zone (Holding Costs and Apportionment) These expenses are often deductible, but may need to be apportioned. Interest on LoansYou can claim interest on the portion of the loan used for the investment property.You cannot claim interest on funds used for personal purposes such as holidays, cars, or private expenses. Example: If you redraw from your mortgage for personal use, you must separate and exclude that portion of interest. Rates and TaxesCouncil rates, water rates, and land tax are generally deductible.You cannot claim water usage charges that are paid directly by the tenant. InsuranceLandlord, building, and contents insurance are deductible.Personal insurance such as life, trauma, or income protection is not. Apportionment RulesIf the property is used privately or is not genuinely available for rent, expenses must be apportioned.This includes: Private stays by the owner Periods where the property is not actively listed for rent Renting below market value III. Claiming Over Time Not all expenses can be claimed immediately. Some must be claimed over several years. Building Write Off (Capital Works)Most residential properties allow a deduction of 2.5 percent per year over 40 years.Eligible build to rent developments may qualify for an accelerated 4 percent rate. Depreciation (Plant and Equipment)Assets such as appliances, carpets, blinds, air conditioning units, and hot water systems are depreciated over their effective life.This is a key area many investors miss or underclaim. RenovationsMajor upgrades such as new kitchens, bathrooms, or extensions are capital works and must be depreciated over time.They should not be claimed as repairs. Instant Asset Write OffThis may apply only if you are genuinely carrying on a rental property business, which is uncommon and depends on your circumstances.Most individual investors will not qualify and will instead claim depreciation over time. IV. The Absolute No List (Common Audit Triggers) Travel ExpensesTravel costs related to inspecting or maintaining a residential rental property are not deductible. This includes flights, fuel, and accommodation. Borrowing Costs Over $100Expenses such as loan establishment fees and lender’s mortgage insurance must be spread over five years. The Leisure Facility Risk (TR 2025/D1)If you use a holiday home privately during peak periods such as Christmas or Easter, the ATO may classify it as a lifestyle asset. The consequence can be severe. The ATO may deny key deductions such as interest, rates, and land tax for the entire year. Keeping accurate records of private use is essential. Investor Action Checklist for 2026 Declare gross income, not net amounts received Review loan redraws and separate personal use Ensure ownership percentages match your tax return Keep a clear record of any private use Confirm your depreciation schedule is up to date Final Word Property investment offers strong tax advantages, but only when structured and reported correctly. Most costly mistakes are not aggressive claims, but simple misunderstandings that compound over time. Getting it right can mean the difference between maximising your return and triggering an ATO review. Need Help Getting This Right? If you are not completely confident your property is structured correctly
House and Land in Donnybrook | Turnkey Townhouse from $586,530
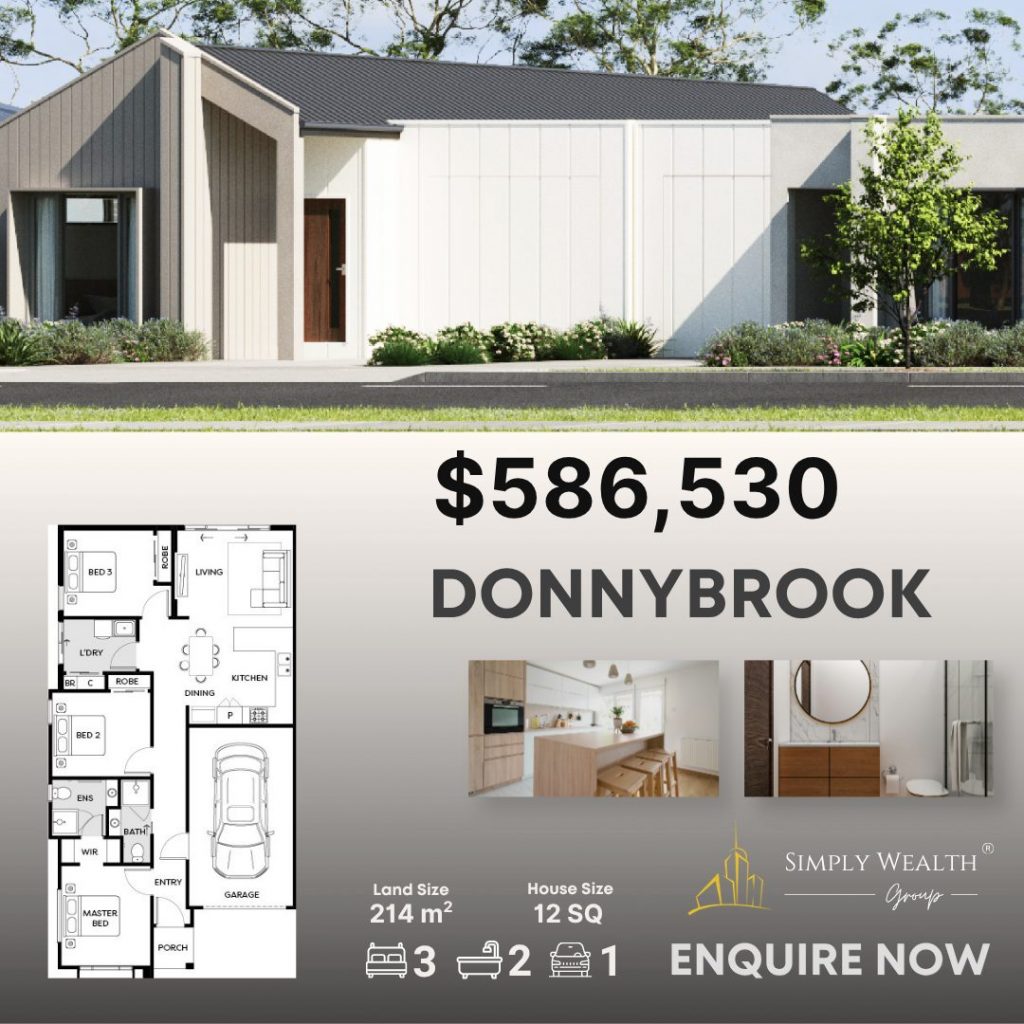
House and Land in Donnybrook. Discover a premium house and land in Donnybrook featuring a modern 3-bedroom turnkey townhouse. Ideal for first home buyers and investors with strong growth potential.
Advice for Young First Home Buyers
Unsurprisingly, one of the biggest hurdles for young people getting a mortgage is affordability. Melisa Sloan, founder of Madison Sloan Lawyers and author of Big Moments said that high demand and property shortages make things even tougher. “The biggest hurdle is affordability and obtaining finance in an environment where property prices, particularly in city areas are relatively high. Saving for a deposit and the ability to service a mortgage has increasingly become difficult for young people over the past two years, with many now reliant on parental or other family help to obtain a mortgage and get into the property market,” said Sloan. “Many people with good jobs and the ability to service a loan find themselves unable to obtain a mortgage because they do not have a sufficient deposit that is required by lenders. Additionally, property shortages continue to make it difficult for people for young people to get a mortgage.” You may read the whole article here:https://bit.ly/4d1mYQg
New Properties for Sale Up 1.3% – PopTrack
New listings in the housing market have increased year-on-year despite a seasonal slowdown, according to the latest PropTrack Listings Report. Compared to the previous month, June 2024 saw new listing volumes down 15%, marking the transition into a quieter season. Every capital city and regional area reported a monthly decrease in new listings in June. However, new listings were 1.3% higher compared to June 2023. Among capital cities, only Perth (-5.7%), Darwin (-6.7%), and Canberra (-2.6%) saw a year-on-year decline in new listings. In regional markets, only South Australia (+8.2%) experienced an increase in new listings over the year. You may read the whole article here:https://bit.ly/4bIZ8rt
Consumer Spending Up Over the Year
According to NAB’s transaction data, consumer spending has remained steady, with total spending on both goods and services flat. Despite this, discretionary spending saw a modest increase of 0.6% month-on-month, while non-discretionary spending declined by 1%. The decrease in non-discretionary spending was primarily due to a significant drop in expenditure on utilities and fuel. Annual growth in consumer spendingConsumer spending is up 5.6% over the past 12 months. However, consumption growth has softened since the beginning of this year, according to Alan Oster, group chief economist at NAB. You may read the whole article here:https://bit.ly/3zPcrcq
ANZ Predicts Possible RBA Rate Hike in August
Despite speculation that the Reserve Bank of Australia (RBA) might raise the official cash rate at its August meeting, ANZ has forecasted that rates will remain unchanged until February 2025, when it predicts a rate cut. The bank noted that while the Reserve Bank kept the cash rate on hold at 4.35% at its June meeting, the post-meeting statement was slightly more hawkish, with the RBA board stating that they are willing to “do what is necessary” to return inflation to target and will remain vigilant to upside risks in inflation. “Following the stronger than expected monthly inflation print for May, there has been some talk about the possibility of a hike at the RBA’s August meeting,” ANZ said in its report, authored by economists Sophia Angala, Madeline Dunk and Catherine Birch. You may read the whole article here:https://bit.ly/3zD0o29
Consumers Fear Rate Hike Impact
An unexpected drop in confidence saw consumer expectations for variable mortgage rates jump 12.8 per cent in July. According to the Westpac-Melbourne Institute’s Mortgage Rate Expectations Index, this is “the steepest monthly rise since we began running this question in every survey at the start of 2022.” The historical average figure of the index is 143.8. In the last three months, however, there has been a 30 per cent surge, with a below-average read of 122.8 in April to 159.2 in July. What is being dubbed a “sudden hawkish turn” is reportedly the most abrupt change seen in the last seven years. Currently, just under 60 per cent of consumers are expecting a mortgage rate rise over the next year. You may read the whole article here:https://bit.ly/3W0gzhj
Bendigo Bank: RBA Cash Rate to Stay Unchanged All Year
Resolve Finance has announced that the 2024 financial year was a record year for the business, with loan volumes surpassing $1.74 billion. This represents a substantial 11% year-on-year increase for the broker franchise, highlighting its continued growth, and success of the franchise business in the highly competitive mortgage broking industry. It comes after a bumper 2023 for the broker network. A significant portion of this growth can be attributed to strong first-time buyer activity. The number of First Home Buyer schemes and grants Resolve brokers have assisted with has increased by 29% from FY23 to FY24. You may read the whole article here:https://bit.ly/4eT0anx
Population Surge Intensifies Housing Shortages
Australia’s national shortage of dwellings has become more critical due to record population growth, according to Hotspotting. In 2023, the country’s population increased by 651,000, the highest in history, with 84% of that growth attributed to overseas migration. “The record level of population growth last year did not cause the shortage of dwellings, including the under-supply of rental homes,” said Terry Ryder director at Hotspotting. You may read the whole article here:https://bit.ly/4bvSa9f
Australian Household Spending up Slightly
Household spending in Australia rose 0.1% over the past year, according to figures recently released by the Australian Bureau of Statistics (ABS). Spending on services increased by 2.3%, driven by higher expenditures on health and other services, while spending on goods fell 2.5%, led by declines in clothing, footwear, and goods for recreation and culture. Non-discretionary spending rose 1.8%, with significant contributions from health expenses and vehicle purchase and operation costs. Discretionary spending decreased by 1.9%, primarily due to reduced spending on clothing, footwear, and accommodation services. You may read the whole article here:https://bit.ly/4cxUJJ0