Locking In Today’s Price: Why Timing Matters More Than Ever in This Market
Most investors get timing backward, as they wait for established prices to fall, then watch building costs rise. Timing matters more than ever because the market is splitting: Melbourne values are softening, yet the ABS says new dwelling prices rose 5.7% in the year to July 2026. Any property investment firm in Melbourne worth trusting will tell you to plan, not predict.
That does not mean rushing in, as a locked price guarantees no growth, and it never replaces solid strategy. It removes one specific risk: paying more later for the same home. Nobody should buy on fear, but everybody should understand what a delay actually costs them.
Is the Market Really Falling Everywhere?
Not quite, as Melbourne dwelling values fell 1.1% in August and now sit about 6% below their November 2025 peak, per Cotality. Nationally, values have slipped five months in a row. Across the capitals, 93% of suburbs recorded a fall through winter. Established buyers have room to negotiate. Most commentary stops there.
New homes tell a different story. The ABS says builders raised base prices to pass on higher labour and material costs. Run that 5.7% over a $700,000 package, and you get about $39,900 a year, or roughly $3,300 a month. Land does not always move in step with build costs, so treat that as an illustration, not a forecast.
What Is the Real Price of Waiting?
The brochure price is only part of the bill, and most buyers discover the rest too late. Delay does not just raise the sticker price. It quietly stacks extra costs on top, and each one lands in your pocket rather than the builder’s. Four pressures matter most:
- Escalation clauses: builders increasingly write them in, so today’s quote may not be your final price.
- Valuation gaps: if costs outrun the bank’s valuation, you cover the difference in cash.
- Borrowing capacity: three RBA hikes this year lifted the cash rate to 4.35%, and each further rise trims what lenders offer.
- Holding costs: delays leave you paying rent and a mortgage at the same time.
Who Do the New Tax Rules Actually Favour?
Parliament passed the changes in June. From 1 July 2027, rental losses on established homes bought after 7:30 pm on 12 May 2026 can’t offset your salary. New builds keep negative gearing. The 50% CGT discount is replaced by indexation and a 30% minimum tax on gains. Source
Canberra designed that carve-out to steer investment toward new supply, which favours house and land packages in Melbourne over established stock. Not every new build qualifies, though. Knock-down rebuilds do not, so confirm eligibility with your accountant before you sign, and read the fine print on any project you consider.
Want to see what a locked-in price looks like for your numbers? Book a free property analysis with Simply Wealth Group.
Is There a Disciplined Way to Lock In Your Price?
Yes, and it looks nothing like panic buying. Discipline means a checklist, not a countdown clock. You refuse any deal that only works if everything goes right, and you test every assumption before you sign. Work through these four steps in order:
- Fix your finance first: test your borrowing capacity at higher rates before you look at any lot.
- Price the whole project: land, build and site costs each carry their own risk, so add them together.
- Scrutinise the contract: provisional sums can blow out, so ask what stays fixed.
- Stress-test your cash flow: run repayments one percentage point above today’s rate, and proceed only if the numbers hold.
Can You Afford to Wait for the RBA?
You can try, but you are betting on something nobody controls. Markets expect the RBA to lift the cash rate again at its 29 September meeting, and the ABS puts annual inflation at 4.60% for July. Even if the RBA pauses afterwards, the board says it remains focused on preventing high inflation from becoming entrenched.
You can refinance a loan when rates ease, as you cannot go back and buy at last quarter’s price. Waiting feels safe, but it is still a decision, and it carries a cost. Disciplined investors rarely wait for perfect conditions. They set a strategy, protect what they can control, and let time do the compounding.
Price You Lock In Is the Only One You Control
Nobody rings a bell at the bottom of a cycle. Rates, values and tax settings will keep moving, and property investors in Melbourne who wait for certainty usually end up paying for it. The build price in your signed contract is the one number you can fix today, while everything else stays open.
The principle is simple: protect the cost you can control, stress-test the rest, and hold for the long term. That is a roadmap, not a rush. Set it once, review it yearly, and resist every headline that tells you to abandon it.
Simply Wealth Group helps everyday Australians build high-performing property portfolios. Our Melbourne-based team invests full-time and guides you every step, from property strategy to mortgage solutions and project management. Explore more at https://simplywealthgroup.com.au/.
Ready to lock in your price? Book your free property analysis or call us today.
FAQs:
How does Simply Wealth Group approach a first purchase?
We put strategy and finance ahead of stock. Your finance broker and wealth strategist matter more than any one property, and our team invests full-time, so the numbers must work first. That reflects our view that ethical advice gives you more than just numbers to decide on.
Why do values fall while build costs rise?
Established values follow borrowing capacity and rates. Build costs follow labour and materials, which builders pass on, while infrastructure and energy projects compete for skilled trades. That is why cheaper established stock and dearer new builds can sit side by side in the same city.
What do current Melbourne packages cost?
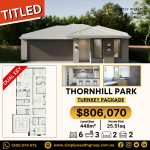
Recent listings on our site run from $574,450 for a compact three-bedroom in Donnybrook to $806,070 for a titled dual-key in Thornhill Park. Prices move, so check availability. Your borrowing capacity, not the advertised price alone, should decide where in that range you shop.
What does another rate rise cost monthly?
About $95 to $125 more a month per 0.25 percentage point on a $600,000 loan, depending on repayment type. Your broker can run exact figures. Knowing that number before you sign keeps a rate move from becoming a surprise during construction.
What happens between signing and handover?
Signing is where the work starts. Delays and stakeholder problems erode budgets, so our project management service handles that, and property management takes over once a tenant moves in. Staying involved through this stage protects the price you locked in, because it is where budgets can slip.
Chat with Simply Wealth Group
Simply Wealth Group
1300 074 675
WhatsApp: 61468175628
marketing@simplywealthgroup.com.a